


The modern automotive industry is transitioning through a massive paradigm shift, evolving from simple transportation machinery to highly integrated, technology-driven mobile platforms. At the heart of this evolution is the digital cockpit, where driver-vehicle interaction is being fundamentally reimagined. Among the technologies leading this charge, the automotive head-up display (HUD) has transformed from a premium novelty into an essential active safety and comfort feature.
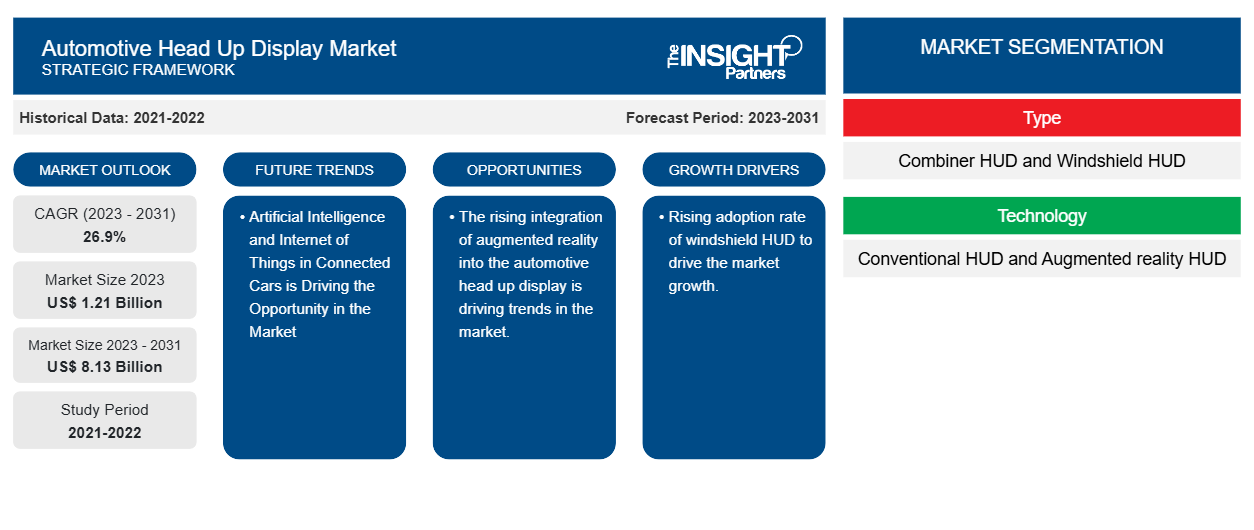
According to an exhaustive market analysis published by The Insight Partners, the Automotive Head Up Display Market size is projected to reach US$ 8.13 billion by 2031 from US$ 1.21 billion in 2023. The market is expected to register a CAGR of 26.9% during 2023–2031. This remarkable growth trajectory highlights the accelerating adoption of digital visual aids in modern vehicles and points to a future where augmented realities and digital overlays become standard aspects of the everyday commute.
Market Dynamics and Primary Growth Catalysts
The immense growth anticipated over the forecast period can be primarily attributed to a surging regulatory focus on driver safety and a parallel consumer demand for advanced driver assistance systems (ADAS). Traditional instrument clusters require drivers to momentarily divert their eyes from the road to check basic metrics like speed or fuel levels. Automotive HUDs eliminate this micro-distraction by projecting critical telemetry, turn-by-turn navigation data, and safety warnings directly into the driver’s natural line of sight.
Furthermore, a significant rise in vehicle production globally, paired with growing disposable income across developing economies, has allowed original equipment manufacturers (OEMs) to democratize HUD technology. Previously restricted to elite, high-end luxury vehicles, automakers like Maruti Suzuki, Hyundai, and BMW are actively integrating sophisticated HUD units into their mass-market and mid-range portfolios.
Technological advancements have also bifurcated the market into distinct offerings: Windshield HUDs and Combiner HUDs. While Combiner units use a small independent screen on the dashboard and offer a cost-effective solution, Windshield HUDs which use the glass surface itself as the screen currently dominate market share. This dominance is driven by the immersive, seamless experience they provide, which blends naturally with advanced liquid crystal displays (LCDs) and light-emitting diodes (LEDs) to yield vibrant, daylight-visible imagery.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPTE100000500
Collaborative Ecosystems and Technological Evolution
Another major pillar supporting the market's explosive CAGR is the widespread adoption of the Internet of Things (IoT) and Artificial Intelligence (AI) in connected cars. Modern HUD units no longer operate in isolation; they are deeply tied to the vehicle's sensor suites, cameras, and external cloud networks. For example, AI-driven HUDs can dynamically adjust brightness based on ambient sunlight or prioritize visual alerts depending on the driver's current cognitive workload and real-time road conditions. This synthesis converts the windshield into an active, intelligent layer of communication rather than just a protective pane of glass.
Key Industry Players
The competitive landscape of the automotive HUD market features a blend of tier-1 automotive suppliers and specialized electronics manufacturers investing aggressively in research and development. The leading market participants shaping this industry include:
Continental AG: A pioneer in automotive electronics, widely recognized for high-volume programs and advanced optical components.
Denso Corporation: Continues to lead high-precision manufacturing, delivering reliable windshield-based projection modules globally.
Robert Bosch GmbH: Leverages its deep expertise in ADAS systems to deliver holistic, safety-first cockpit solutions.
Harman International: Focuses on immersive user experiences, notably through software-hardware products like their "Ready Vision" AR suite.
Yazaki Corporation: Contributes vital underlying electronic interfaces and display systems tailored for various vehicle architectures.
Valeo: Drives innovation through localized display solutions and next-generation driver-assistance technologies.
Nippon Seiki Co., Ltd: Holds substantial market footprint specifically specializing in instrument clusters and advanced HUD optics.
Panasonic Automotive Systems Europe GmbH: Expands the boundaries of in-car tech, notably pushing AI-based holographic and dual-plane views.
HUDWAY, LLC: Acts as a key innovator in portable and aftermarket HUD applications, making the tech accessible across retrofitted segments.
Japan Display Inc: Provides the fundamental high-resolution, high-brightness panel technologies critical to keeping displays visible in extreme daylight.
Future Outlook
Looking ahead, the automotive head-up display market is set to experience an exciting evolutionary leap as the industry transitions fully to electric vehicles (EVs) and autonomous driving environments. Moving beyond the conventional 2D projection systems of the past, the future belongs entirely to Next-Gen Augmented Reality HUDs (AR-HUDs). These advanced displays use sophisticated holographic waveguides to place graphics, such as destination points and lane warnings, at a true depth that corresponds to the physical road layout ahead. As autonomous driving capabilities mature, the role of the HUD will expand from an informational driving tool to an expansive, context-aware entertainment and communication interface. Driven by declining optical module costs and an industry-wide push for software-defined vehicles, the windshield is destined to become the primary interactive layer of the future mobility ecosystem.
Related Reports-
Airport Display Systems Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
The construction industry is undergoing a massive paradigm shift, driven by the critical need for speed, sustainability, and cost efficiency. At the forefront of this evolution is the prefabricated housing sector. Prefabricated housing, which involves manufacturing building components or entire structures in a controlled factory environment before transporting them to a site for final assembly, has transformed from a niche alternative into a core pillar of modern residential development.
According to a comprehensive industry study by The Insight Partners, the global Prefabricated Housing Market size is projected to reach US$ 292.72 billion by 2034 from US$ 168.81 billion in 2025. The market is anticipated to register a CAGR of 6.31% during the forecast period 2026-2034. This significant growth trajectory highlights the accelerating adoption of off-site construction methods worldwide as governments, developers, and consumers seek smarter alternatives to traditional brick-and-mortar building processes.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global food industry is undergoing a massive transformation, fueled by shifting consumer preferences, technological breakthroughs, and an increasing focus on sustainability. At the heart of this evolution is the machinery that processes, transforms, and packages what we eat. As food manufacturers race to meet the demands of a growing, urbanizing global population, advanced equipment has transitioned from a competitive advantage to an absolute necessity.
According to a comprehensive study by The Insight Partners, the global food processing machinery market is on a robust growth trajectory. The Food Processing Machinery Market size is expected to reach US$ 133.03 Billion by 2034 from US$ 77.77 Billion in 2025. The market is estimated to record a CAGR of 6.15% from 2026 to 2034. This steady expansion highlights the massive capital investments being made by food and beverage companies to automate their operations and extend product shelf lives.
Key Growth Drivers in the Global Market
Several interconnected factors are pushing the market forward. Chief among them is the explosive rise in the consumption of processed and convenient ready-to-eat foods. Modern lifestyles leave consumers with less time for meal preparation, sparking unprecedented demand for frozen foods, packaged snacks, and pre-cut produce. Processing this vast array of items uniformly and safely requires specialized machinery capable of handling high volumes without sacrificing nutritional value or taste.
Simultaneously, stringent regulatory standards regarding food safety and hygiene are forcing manufacturers to upgrade outdated infrastructure. Modern equipment features sanitary designs, utilizing specialized stainless steel alloys and automated Clean-in-Place (CIP) systems that dramatically reduce the risk of microbial contamination. Furthermore, there is an industry-wide push toward sustainable manufacturing. Modern processing machinery is engineered to minimize energy use, optimize water consumption, and reduce food waste during raw material handling, perfectly aligning corporate operations with stricter environmental regulations.
Market Segmentation and Technology Integration
The food processing machinery sector spans a wide range of specialized equipment designed for distinct stages of manufacturing. This includes initial pre-processing systems, mechanical processing gear like mixing, cutting, and grinding units, thermal processing systems such as ovens and pasteurizers, and final-stage packaging machinery.
The integration of Industry 4.0 technologies is completely reshaping these categories. Modern processing lines are increasingly outfitted with smart sensors and Internet of Things (IoT) connectivity. This allows factory operators to monitor machine health, temperature variations, and throughput metrics in real time. Predictive maintenance algorithms can alert engineers to potential component failures before they happen, preventing costly unscheduled downtime and keeping factory yields high.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00009305
Prominent Industry Innovators
The competitive landscape of the global food processing machinery market is characterized by prominent players focusing on continuous product innovation, strategic mergers, and geographical expansion to strengthen their market presence. A few of the key players steering development across various sectors of the industry include:
ANKO FOOD MACHINE CO., LTD. – A prominent leader in automated ethnic food processing equipment, specializing in dumpling, pastry, and bakery machinery.
Atlas Pacific – Renowned globally for providing highly efficient fruit processing machinery, particularly peeling, coring, and slicing systems.
Bühler technologies – A massive global force in grain processing, chocolate manufacturing, and advanced sorting solutions.
GEA Group Aktiengesellschaft – An industry heavyweight delivering integrated processing systems, separation technologies, and liquid handling systems for dairy, beverage, and food sectors.
Hosokawa Micron Group – Experts in powder and particle processing technology, serving niche requirements in food ingredient formulation.
JBT (John Bean Technologies) – Provides comprehensive high-value solutions for poultry, meat, fruit, juice, and automated systems.
NICHIMO CO., LTD. – A highly specialized player known for maritime, seafood processing, and advanced food manufacturing machinery.
SPX FLOW, Inc. – Engineers high-precision flow components, process systems, and turn-key solutions tailored for the dairy and beverage industries.
Tetra Pak International S.A. – The definitive global standard-bearer in food processing and aseptic packaging solutions.
Vantage Specialty Chemicals – While focusing on specialty chemical formulations, they provide critical food-grade processing aids, lubricants, and release agents that ensure the smooth and safe operation of complex mechanical lines.
Future Outlook
Looking toward the future, the food processing machinery market is positioned to lean heavily into hyper-automation, artificial intelligence (AI), and tailored customization. As labor shortages continue to impact manufacturing hubs worldwide, the reliance on fully autonomous processing lines and robotic handling systems will naturally accelerate. AI-driven vision inspection systems will become standard for automated quality control, instantly identifying and discarding sub-par products with human-defying accuracy. Additionally, as consumer trends tilt rapidly toward plant-based proteins, clean-label ingredients, and personalized nutrition, processing equipment will need to become more modular and flexible. Manufacturers who invest in highly versatile, energy-efficient machinery that can easily pivot between different product lines will undoubtedly lead the market through 2034 and beyond.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
Modern warfare is no longer constrained by the setting of the sun. The ability to dominate the battlespace under the cover of darkness has evolved from a tactical advantage into an absolute strategic necessity. As global defense forces prioritize 24/7 operational readiness and asymmetric warfare capabilities, the technologies that enable soldiers to see, target, and navigate in zero-light environments are experiencing unprecedented demand.
According to a comprehensive study by The Insight Partners, the global Military Night Vision System Market size is projected to reach US$ 14.73 billion by 2034 from US$ 9.57 billion in 2025. This steady growth is anticipated to register a compound annual growth rate (CAGR) of 5.54% during the forecast period from 2026 to 2034.
Primary Catalysts Driving Market Expansion
Several macroeconomic and geopolitical dynamics are converging to fuel the growth of the military night vision market. Chief among these is the escalating level of geopolitical tension worldwide. Border disputes, counter-terrorism operations, and the rise of gray-zone warfare have forced nations to modernize their infantry and specialized units. Defense departments are heavily investing in personal soldier equipment to maximize survivability and combat lethality.
Furthermore, night-time missions are statistically preferred for covert operations, reconnaissance, and surgical strikes. To execute these safely, defense forces require systems that offer maximum clarity, extended range, and minimal latency. This has shifted the market focus from basic image intensification to advanced digital and hybrid fusion systems.
Technological Shifts: From Intensification to Sensor Fusion
The military night vision landscape is undergoing a massive technological transition. Traditionally, systems relied purely on Image Intensification (I2) tubes, which amplify ambient light (like starlight or moonlight) to create a visible image. While newer Generation 3 and Generation 4 I2 systems are incredibly sensitive and power-efficient, they struggle in absolute darkness, such as deep caves or subterranean structures.
To mitigate this, the industry is rapidly adopting Sensor Fusion Technology. Fusion systems combine traditional image intensification with thermal imaging (infrared sensors that detect heat signatures). By overlaying a thermal outline onto a high-resolution ambient image, soldiers can spot a hidden enemy behind foliage or camouflage while maintaining clear environmental awareness.
Additionally, the integration of Augmented Reality (AR) overlays onto night vision goggles allows real-time tactical data such as navigation waypoints, blue-force tracking, and target markers to be projected directly into the operator's field of view.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00006030
Competitive Landscape and Key Players
The military night vision system market is highly competitive, characterized by established defense giants and specialized electro-optical component manufacturers. These entities focus on securing long-term government contracts, reducing the size, weight, and power (SWaP) metrics of devices, and improving digital resolution.
Prominent players driving innovation and holding significant market share include:
ATN Corp – Renowned for commercial and tactical smart digital night vision and thermal optics.
BAE Systems – A global defense leader providing advanced integrated helmet systems and digital night vision technologies.
Bharat Electronics Limited (BEL) – A premier Indian defense PSU supplying night vision goggles, weapon sights, and binoculars to domestic and international forces.
Collins Aerospace – Specializes in high-performance airborne and ground electro-optical systems.
Elbit Systems Ltd. – An international defense electronics company at the forefront of sophisticated helmet-mounted displays and fusion goggles.
FLIR Systems, Inc. (A Teledyne Technologies Company) – Global pioneer in thermal imaging sensors and infrared surveillance systems.
Intevac, Inc. – Renowned for its digital night vision sensors, particularly low-light CMOS technology utilized in military aviation.
L3Harris Technologies, Inc. – A dominant supplier of next-generation night vision goggles (such as the ENVG-B) featuring integrated thermal and AR capabilities for the US military.
Photonis Technologies SAS – A crucial manufacturer of high-performance image intensifier tubes used by various global device assemblers.
Thales Group – A European defense leader providing cutting-edge, lightweight optronics and night vision sights for dismounted soldiers.
Segmental and Regional Insights
Geographically, North America currently holds a dominant position in the market, primarily driven by the massive procurement budgets of the US Department of Defense and continuous soldier modernization programs. However, the Asia-Pacific region is poised to display the fastest growth rate over the forecast period. Countries like India, China, and South Korea are aggressively updating their military hardware to counter local security threats, creating a highly lucrative environment for domestic and foreign electro-optics manufacturers.
In terms of systems, helmet-mounted devices and weapon-mounted sights remain the highest-volume segments, though vehicular and airborne night-vision installations are seeing stable growth to support armored units and nighttime aviation logistics.
Future Outlook
The future of the military night vision system market lies in full digitalization and software-defined optics. As standard analog tubes gradually give way to digital low-light sensors, future systems will easily integrate into broader battlefield management networks. We can expect artificial intelligence (AI) to play a crucial role at the edge, offering automatic target recognition (ATR) and filtering out environmental noise like smoke, dust, or sudden flash blindness. As manufacturers successfully lower the cost of sensor fusion and digital components, these advanced capabilities will transition from elite special forces down to standard infantry, ensuring that tomorrow's military forces maintain unchallenged supremacy in the dark.
Related Reports-
Enhanced Flight Vision System Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global aviation landscape is undergoing an unprecedented evolution. As passenger volumes surge and commercial airlines expand their fleets, the complexity of managing global airspace has escalated dramatically. To keep pace with this demand, the global Air Traffic Management (ATM) industry is embracing sweeping structural and technological transformations.
According to a comprehensive industry report by The Insight Partners, the Air Traffic Management Market size is projected to reach US$ 9.85 Billion in 2025 and is expected to reach US$ 16.56 Billion by 2034. The market is expected to register a CAGR of 7.31% during the forecast period. This steady growth highlights an urgent, industry-wide push to modernize aging aviation infrastructure, optimize fuel consumption, and ensure the highest standards of safety across international borders.
Driving Forces Behind Modern Air Traffic Management
The growth of the ATM market is fueled by a combination of recovering passenger demand, regulatory mandates, and the emergence of new airborne technologies. Legacy radar-based control systems are gradually reaching their capacity limits. As a result, civil aviation authorities and airport operators worldwide are turning toward integrated digital platforms to maximize airspace efficiency.
Key drivers reshaping the ATM ecosystem include:
Airspace Congestion and Capacity Optimization: Major international hubs face daily bottlenecks that ripple across regional networks. Modern ATM systems utilize precise data analytics to sequence arrivals and departures closer together without compromising safety margins.
Decarbonization and Green Routing: Airlines are under immense pressure to lower carbon emissions. Advanced ATM software enables "Trajectory-Based Operations" (TBO), allowing aircraft to fly optimized, fuel-efficient paths rather than rigid, legacy airways.
Unmanned Traffic Integration: The rapid proliferation of commercial drones, logistics quadcopters, and Urban Air Mobility (UAM) concepts demands a unified infrastructure. Traditional ATM systems are evolving into Unmanned Traffic Management (UTM) ready ecosystems to manage low-altitude traffic.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00005933
Key Market Competitors
The global ATM landscape features a mix of aerospace giants, defense conglomerates, and specialized software developers providing hardware, communications networks, and surveillance systems. Prominent entities shaping the market include:
Advanced Navigation and Positioning Corporation
BAE Systems PLC
Harris Corporation
Honeywell International, Inc.
Intelcan Technosystems Inc.
Lockheed Martin Corporation
Raytheon Company
SAAB AB
Saipher ATC
Thales Group
These market participants focus heavily on collaborative partnerships with national Air Navigation Service Providers (ANSPs) to roll out next-generation software architectures, artificial intelligence diagnostic tools, and resilient cybersecurity frameworks.
Technical Innovations: Automation, Cloud, and AI
At the heart of the modern ATM transformation is the shift toward automation and digital twins. Traditional control towers are increasingly supplemented or replaced by Remote Digital Towers (RDTs). Using high-definition cameras, infrared sensors, and real-time telemetry, controllers can safely manage airport operations from hundreds of miles away—a breakthrough particularly beneficial for managing multiple low-volume regional airports from a centralized hub.
Furthermore, artificial intelligence is migrating from a theoretical tool to active operational support. AI algorithms analyze historical flight data, current weather conditions, and aerodynamic wake turbulence patterns to predict potential traffic conflicts up to an hour before they occur. This predictive capability shifts the air traffic controller's role from reactive management to proactive routing.
Regional Variations in Infrastructure Upgrades
The deployment of these systems varies significantly across geographic regions:
North America & Europe: Driven heavily by well-established modernization frameworks like NextGen (FAA) and SESAR (Single European Sky ATM Research). The focus in these regions centers on satellite-based navigation, digital data communications (Data Comm), and tight integration of cybersecurity layers to defend critical aviation networks.
Asia-Pacific & Middle East: Experiencing massive infrastructure investments due to new airport constructions and major fleet expansions by regional carriers. ANSPs in these markets are investing aggressively in high-capacity automation platforms and advanced surveillance tools to cope with some of the densest air corridors in the world.
Future Outlook
The future of the Air Traffic Management market points toward an interconnected, cloud-native aviation ecosystem. Over the coming decade, traditional siloed national architectures will give way to cross-border, cloud-based data sharing networks. This shift will allow for seamless regional flight handoffs and significantly reduced flight delays. Additionally, as machine learning algorithms assume greater responsibility for routine routing adjustments, human controllers will transition to strategic supervisors overseeing automated workflows. The integration of artificial intelligence, green flight paths, and low-altitude drone tracking will redefine global airspace, ensuring that the skies remain highly scalable, environmentally conscious, and safe for decades to come.
Related Reports-
Air Traffic Control Equipment Market
Commercial Air Traffic Management Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The automotive industry is undergoing a monumental shift, transitioning from traditional mechanical engineering to software-defined, highly connected vehicles. At the heart of this evolution lies the automotive switch a seemingly basic component that serves as the crucial interface between the vehicle's driver, passengers, and its electronic ecosystem. As modern vehicles adopt increasingly sophisticated electronic architectures, the automotive switch market is witnessing consistent and healthy growth.
The Automotive Switch Market is expected to register a CAGR of 4.08% from 2026 to 2034, with the market size expanding from US$ 55.33 Billion in 2025 to US$ 79.29 Billion by 2034. This growth is fueled by a combination of stricter automotive safety mandates, an increase in standard electronic comfort features, and the global adoption of electric vehicles (EVs).
Market Dynamics and Drivers
A key catalyst accelerating the automotive switch market is the massive influx of consumer electronic features into cars. Today’s consumers demand the same level of touchscreen responsiveness, ambient lighting control, and digital convenience in their vehicles that they experience with smartphones and tablets. Consequently, conventional toggle and rotary switches are rapidly making way for smart touchpads, haptic feedback buttons, and multi-functional steering wheel controls.
Furthermore, the electrification of vehicles plays an instrumental role. Electric vehicles utilize sophisticated electronic control units (ECUs) to manage everything from battery cooling systems to advanced driver-assistance systems (ADAS). This expansion of a vehicle's electrical framework naturally requires an increased quantity of high-voltage and low-voltage switches to reliably regulate power and signal transmission.
Safety regulations mandated by governments globally also serve as a vital market driver. Standards requiring standard inclusion of backup cameras, electronic stability control, and automated emergency braking systems necessitate a dense array of sensory and manual override switches inside the cabin and under the hood.
Segmentation Overview
The automotive switch market can be segmented based on switch type, application, vehicle type, and geography. By switch type, the market includes push-button switches, toggle switches, rotary switches, and multi-function steering switches. Among these, multi-function steering and haptic smart switches are gaining substantial market share due to their role in reducing driver distraction.
In terms of application, switches are widely classified into powertrain systems, chassis systems, body electronics, and infotainment systems. The body electronics and comfort systems segment accounts for a considerable share, driven by features like power windows, electronic seat adjustments, sunroof controls, and motorized mirrors. By vehicle type, the passenger car segment continues to lead the demand, though commercial vehicles are gradually catching up as logistics companies upgrade to telematics-equipped smart trucks.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00023840
Competitive Landscape: Key Market Players
The global automotive switch market is highly competitive and characterized by the presence of prominent tier-1 automotive suppliers and electronics manufacturers. These enterprises are actively focusing on strategic product launches, lightweight component designs, and smart switch technologies to sustain their market positions.
The key players dominating this market landscape include:
Alps Electric Co., Ltd.
Continental AG
Hella KGaA Hueck and Co.
Johnson and Johnson
Omron Corporation
Panasonic Corporation
Robert Bosch GmbH
Tokai Rika Co., Ltd.
Valeo
ZF Friedrichshafen AG
These industry leaders heavily invest in Research and Development (R&D) to engineer switches capable of handling harsh automotive conditions such as extreme temperatures, high vibration, and moisture while maintaining ergonomic and aesthetic appeal.
Regional Analysis
Geographically, Asia-Pacific remains the powerhouse of the automotive switch market. The region’s dominance is anchored by massive automotive production hubs in China, Japan, India, and South Korea. Increased consumer spending power, paired with a rising demand for premium passenger cars featuring advanced cabin comfort, further accelerates the regional market.
Europe and North America represent highly mature markets. In these regions, growth is heavily supported by rigid safety standards and a swift consumer transition toward premium luxury electric vehicles. Original Equipment Manufacturers (OEMs) in Europe and North America are focusing tightly on integrating intelligent touch-capacitive panels, forcing traditional switch manufacturers to modernize their current portfolios.
Future Outlook
The future of the automotive switch market is inextricably linked to the concepts of vehicle autonomy, intuitive human-machine interfaces (HMI), and premium cabin interior design. Moving forward, the distinction between a mechanical switch and a digital screen will continue to blur. We can expect to see a surge in "smart surfaces" where switches are seamlessly integrated into wooden dashboards, leather doors, or glass panels, becoming visible and operational only when a hand approaches. As autonomous driving technology matures and drivers transition into passengers, the interior vehicle cabin will transform into a mobile living space, generating a massive need for localized, highly sophisticated switches that prioritize luxury, gesture control, and personalized comfort. The ongoing expansion toward a US$ 79.29 Billion valuation by 2034 stands as a testament to the enduring, critical role that switches will play in the smarter, safer vehicles of tomorrow.
Related Reports-
Automotive Steering Wheel Switch Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The automotive manufacturing sector relies on a highly complex, interconnected global supply chain where millions of components ranging from heavy steel engines to microscopic electronic sensors must be transported safely across continents. As vehicle designs shift toward advanced electronics and electrification, the protective systems handling these components are undergoing a parallel evolution.
The Automotive Packaging Market size is expected to reach US$ 13.18 Billion by 2034 from US$ 9.27 Billion in 2025. The market is estimated to record a CAGR of 4.50% from 2026 to 2034. This steady expansion underscores the crucial role that specialized logistics and packaging solutions play in modern automotive manufacturing and the aftermarket sector.
Key Drivers Shaping the Market
Several macroeconomic and industry-specific shifts are steering the development of the automotive packaging sector:
The Transition to Electric Vehicles (EVs): Unlike traditional internal combustion engines, electric vehicles depend on massive, highly sensitive lithium-ion battery packs, power electronics, and intricate wiring systems. These components require unique packaging solutions that offer thermal insulation, impact resistance, and compliance with stringent international regulations for hazardous materials.
Rising Electronic Complexity: The integration of Advanced Driver Assistance Systems (ADAS), autonomous driving technologies, and infotainment screens has turned modern cars into computers on wheels. Fragile semiconductor-based parts are highly vulnerable to electrostatic discharge (ESD), moisture, and physical vibrations during transit. Protective packaging using specialized anti-static films, custom molded foam, and robust cushioning is vital to prevent multi-million dollar supply chain losses.
The Push for Circular Economies: Automakers are facing heavy pressure from regulatory frameworks and internal corporate social responsibility (CSR) targets to reduce their carbon footprint. This has accelerated the transition from single-use, disposable packaging to returnable and reusable systems. Reusable plastic crates, steel racks, and bulk containers offer long-term cost efficiencies and minimize waste.
Just-In-Time (JIT) Manufacturing: To save on warehousing costs, original equipment manufacturers (OEMs) operate on tight JIT delivery schedules. Packaging must be standardized, modular, easily stackable, and collapsible when empty to maximize shipping container space and optimize inbound and outbound logistics.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00026590
Material and Segment Insights
The global market features a balanced blend of rigid, flexible, and corrugated solutions designed to handle specific component categories:
Rigid Packaging (Crates, Pallets, and Racks): Heavy components like engines, gearboxes, and suspension systems are transported via heavy-duty, reusable plastic and steel racks. These provide maximum structural protection and are built to handle multiple round trips across supply chain routes.
Corrugated Solutions: Corrugated cardboard boxes and die-cut custom packaging remain highly popular for medium and small-sized spare parts due to their lightweight properties and high recyclability. Advanced corrugated designs offer strong barrier properties and shock resistance at lower initial costs.
Flexible and Protective Packaging: Bubble wraps, expanded polypropylene (EPP) foam inserts, and protective pouches are critical layers within outer boxes. They shield sensitive surfaces from scratches and absorb transit vibrations, ensuring components arrive at the assembly line in pristine condition.
Competitive Landscape
The automotive packaging industry is highly competitive, with global and regional players continuously innovating to introduce lighter, stronger, and more sustainable materials. Companies focus on strategic partnerships with OEMs and invest heavily in localized fabrication to meet precise geometric requirements for vehicle parts.
Key players driving innovation and operational scale within the market include:
Nefab Group
New-Tech Packaging
Kronus
D S Smith
Victory Packaging
Schoeller Allibert
Orcon Industries
PRIMO
Robinson Industries
THIMM Group
Future Outlook
The future of the automotive packaging market will be defined by smart technology and deep sustainability integration. We can expect a significant increase in the adoption of "smart packaging" systems embedded with RFID tags, IoT sensors, and GPS trackers. These technologies will allow logistics managers to monitor the precise location, temperature, and shock exposure of high-value parts like EV batteries in real time. Furthermore, innovations in bio-based plastics and high-strength, lightweight paper composites will help manufacturers satisfy stringent global eco-regulations while driving down shipping weights. As global vehicle production volumes stabilize and move deeper into the electric era, packaging will cease to be treated as a mere transit cost and will instead become a core pillar of lean, digitalized, and green automotive logistics.
Related Reports-
Flexible Packaging Solutions Market
Temperature Controlled Packaging Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global industrial landscape is experiencing a massive shift toward sustainability and operational optimization, placing a renewed focus on energy-efficient thermal management systems. Air-cooled heat exchangers (ACHEs) crucial systems used to reject heat from a process fluid directly into the ambient air have emerged as a vital technology across multiple heavy industries. According to a comprehensive research study by The Insight Partners, the global market for these systems is poised for exponential growth over the next decade.
The Air-Cooled Heat Exchangers Market size is expected to reach US$ 8.92 Billion by 2034 from US$ 4.68 Billion in 2025.The market is estimated to record a CAGR of 8.40% from 2026 to 2034. This robust growth trajectory is heavily driven by increasing water scarcity, stricter environmental regulations regarding thermal pollution, and a widespread industrial push toward lowering operational costs.
Market Dynamics and Primary Growth Drivers
Traditional cooling systems heavily rely on water, such as shell-and-tube heat exchangers coupled with cooling towers. However, massive industrial expansion in water-scarce regions has made water conservation a top priority for global enterprises. Air-cooled heat exchangers present an eco-friendly and highly practical alternative because they eliminate the need for an external water supply, thereby removing costs associated with water treatment, chemical conditioning, and disposal.
Furthermore, regulatory frameworks worldwide are tightening constraints on thermal water discharge, which can disrupt aquatic ecosystems when hot water is released back into natural bodies. By utilizing ambient air as the cooling medium, industries can seamlessly comply with strict environmental mandates. Technological advancements are also reshaping the market landscape.Manufacturers are leveraging innovative designs, specialized finned configurations, and eco-friendly materials to dramatically boost thermal efficiency, allowing ACHEs to perform exceptionally well even in high ambient temperature environments.
Segmentation Overview
To provide a detailed outlook of the marketplace, the air-cooled heat exchangers market is categorized into distinct segments based on configuration, material, and end-use industry:
By Configuration: The market is analyzed across Forced Draft, Induced Draft, Horizontal, Vertical, and A-frame designs. Forced draft configurations are highly favored for their ease of maintenance and structural stability, while induced draft units offer superior air distribution and reduced hot air recirculation.
By Material: Material selection is vital for ensuring corrosion resistance and thermal conductivity. The market is segmented into Stainless Steel, Carbon Steel, and Copper, with stainless steel witnessing significant demand in corrosive or highly hygienic industrial processes.
By Industry: ACHEs serve as critical infrastructure across a diverse array of sectors, including Cement, Chemical, Pharmaceutical, Power, Steel, and Oil and Gas. The oil and gas and power generation sectors remain dominant consumers due to the massive scale of cooling required in refineries and thermal power plants.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00025309
Competitive Landscape and Key Players
The global air-cooled heat exchangers market features a blend of established engineering conglomerates and specialized thermal management providers. These entities are consistently investing in research and development, strategic partnerships, and geographic expansions to secure a competitive edge.
The key players operating in the market include:
Alfa Laval
Boldrocchi
Chart Industries
Fbm Hudson Italiana
Howden Group
Kawasaki Heavy Industries, Ltd.
Paharpur Cooling Towers Ltd.
SPG Dry Cooling
SPX Cooling Technologies, Inc.
Thermax Limited
These industry leaders focus on delivering customized, highly reliable, and heavy-duty thermal systems tailored to survive harsh operational environments, ranging from sub-zero arctic oil fields to scorching desert chemical plants.
Regional Market Insights
Geographically, the market spans North America, Europe, Asia-Pacific, South & Central America, and the Middle East & Africa. The United States represents a pivotal hub within North America, heavily supported by a booming oil and gas sector, expanding chemical processing facilities, and a rapid adoption of green technology.
Meanwhile, the Asia-Pacific region is projected to experience the fastest growth rate through 2034. Massive industrialization, continuous infrastructure development in nations like China and India, and the rising demand for electricity are triggering substantial investments in new power and steel manufacturing plants, fueling the regional demand for industrial cooling solutions.
Future Outlook
The future of the air-cooled heat exchangers market points toward hyper-efficiency and digital integration.As industries embrace digital transformation and the Industrial Internet of Things (IIoT), smart monitoring systems are revolutionizing ACHE maintenance.Future designs will increasingly incorporate artificial intelligence (AI) and advanced sensors to predict mechanical failures, monitor fouling, and dynamically adjust fan speeds based on real-time ambient weather conditions. This evolution will dramatically lower energy consumption and mitigate unplanned downtime. Combined with the global transition toward green technologies such as hydrogen production and carbon capture systems, both of which require specialized thermal management the demand for advanced, eco-friendly air-cooled heat exchangers is set to remain exceptionally strong, ensuring a sustainable and profitable horizon for manufacturers worldwide.
Related Reports-
Automotive Heat Exchanger Market
Air Separation Equipment Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global industrial landscape is undergoing a massive transformation, driven by automation, infrastructure development, and the relentless demand for heavy-duty machinery. At the heart of this machinery lies fluid power technology. The mobile hydraulic equipment market is experiencing significant growth, fueled by advancements in construction, agriculture, material handling, and mining sectors worldwide. As industries seek more reliable, efficient, and powerful systems to operate heavy vehicles and machinery, mobile hydraulics have become indispensable.
Market Size and Growth Trajectory
According to a comprehensive study by The Insight Partners, the market for mobile hydraulic equipment is on a strong upward trajectory. The Mobile Hydraulic Equipment Market size is expected to reach US$ 23.88 Billion by 2034 from US$ 15.64 Billion in 2025. The market is estimated to record a CAGR of 5.43% from 2026 to 2034. This steady compound annual growth rate reflects the sustained demand for modernized machinery that can withstand harsh operating environments while delivering high power-to-weight ratios.
Driving Factors behind Market Expansion
Several factors are propelling the growth of the mobile hydraulic equipment market. First and foremost is the rapid pace of urbanization and infrastructure development, particularly in emerging economies across the Asia-Pacific and Latin American regions. Governments are investing heavily in smart cities, roadways, bridges, and commercial complexes, all of which require robust construction equipment like excavators, loaders, and cranes equipped with advanced hydraulic systems.
Furthermore, the agricultural sector is adopting high-tech mechanization to increase yield and combat labor shortages. Modern tractors, harvesters, and forestry equipment rely heavily on mobile hydraulics for precise steering, lifting, and tool attachments. Similarly, the e-commerce boom has drastically increased the demand for material handling equipment, such as forklifts and automated guided vehicles (AGVs) in warehouses, further driving market volume.
Technological advancements are also rewriting the rules of the industry. The integration of electronics with fluid power commonly known as electro-hydraulics has allowed manufacturers to design systems with improved energy efficiency, reduced emissions, and superior control accuracy.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00023694
Key Industry Players
The mobile hydraulic equipment market is highly competitive, with several prominent players focusing on innovation, strategic partnerships, and geographical expansion to maintain their market dominance. The leading companies shaping the market include:
JWF Technologies: Known for designing and distributing customized fluid power and motion control systems.
Rheintacho Messtechnik GmbH: A specialist in rotational speed sensors and monitoring systems essential for hydraulic safety and efficiency.
HAWE Hydraulik SE: Highly regarded for its high-pressure hydraulic components and compact systems.
Bosch Rexroth Corporation: A global giant leading the wave of digital transformation and electro-hydraulic solutions.
Daikin Industries Ltd.: Recognized for combining advanced cooling systems with efficient hydraulic power units.
Eaton: A long-time leader in power management, providing durable hydraulic pumps, valves, and cylinders.
Emerson Electric Co.: Delivering smart pneumatic and fluid control technologies that complement mobile hydraulic applications.
Kawasaki Heavy Industries, Ltd.: A pioneer in high-capacity hydraulic pumps and motors used extensively in heavy construction equipment.
Parker Hannifin Corporation: A global leader in motion and control technologies, offering one of the broadest portfolios of hydraulic solutions.
WEBER-HYDRAULIK GmbH: Renowned for developing customized, high-quality hydraulic cylinders and lifting systems.
These organizations are continuously investing in research and development (R&D) to build lighter, more compact, and leak-free hydraulic solutions that meet stringent global environmental regulations.
Future Outlook
The future of the mobile hydraulic equipment market is deeply intertwined with sustainability and digitalization. Over the next decade, the industry is expected to witness an accelerating shift toward "smart hydraulics." By embedding IoT sensors and data analytics into hydraulic components, operators can perform predictive maintenance, thereby reducing costly equipment downtime and optimizing fuel consumption.
Additionally, the global push toward electrification poses both a challenge and an incredible opportunity for the market. While purely electric actuators are emerging, they often lack the sheer power density required for heavy lifting. Consequently, the industry is moving toward hybrid electro-hydraulic systems, which marry the high force capability of traditional hydraulics with the clean efficiency of electric powertrains. As eco-friendly bio-degradable hydraulic fluids gain mainstream traction alongside these hybrid systems, the mobile hydraulic equipment market is well-positioned to maintain its vital role in global industrial progress well into 2034 and beyond.
Related Reports-
Axial Piston Hydraulic Motors and Pumps Market
Hydraulic Torque Wrench Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global energy landscape is undergoing a massive transformation. As industries and governments work together to reduce carbon emissions while simultaneously meeting a soaring global demand for electricity, the underlying infrastructure must evolve. At the heart of this transition is the industrial gas turbine—a highly efficient internal combustion engine that converts natural gas or other liquid fuels into mechanical energy to drive electrical generators. Today, these systems are no longer just basic utilities; they are critical pillars supporting modern electrical grids, industrial operations, and decentralized energy hubs.
According to a comprehensive market study by The Insight Partners, the global Industrial Gas Turbine Market size is projected to reach US$ 13.54 billion by 2034 from US$ 9.96 billion in 2025. The market is anticipated to register a CAGR of 3.91% during the forecast period 2026-2034. This steady upward trajectory highlights a sustained reliance on gas-fired infrastructure as a primary bridging mechanism toward a more sustainable, low-carbon future.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876