

The Wheat Bran Market was valued at US$ 22.97 billion in 2025 and is projected to reach US$ 31.27 billion by 2034, registering a CAGR of 3.93% during 2026–2034. The market is expanding as demand increases for high-fiber, nutrient-rich ingredients across food, nutrition, nutraceutical, and animal feed applications.
Wheat bran, a by-product of wheat milling, is gaining importance as manufacturers seek functional ingredients that support nutritional enhancement, clean-label positioning, and more efficient utilization of agricultural resources.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00018926/
What is driving the market?
Growing health awareness, demand for dietary fiber, food-product innovation, and sustainable utilization of milling by-products are the principal growth drivers.
Consumers are increasingly focused on digestive health, weight management, balanced nutrition, and clean-label foods. Wheat bran's high dietary fiber content makes it attractive for incorporation into products designed to provide enhanced nutritional value. Food manufacturers are therefore expanding its use beyond conventional applications into high-fiber breads, breakfast cereals, nutritional bars, snacks, and other functional food formulations.
Innovation across food applications is also supporting demand. Manufacturers are developing products that incorporate wheat bran while improving taste, texture, digestibility, and overall consumer acceptance. Its versatility allows producers to respond to changing dietary preferences without relying exclusively on conventional refined ingredients.
Sustainability is another important factor. Wheat bran is generated during wheat milling, and its utilization in food, feed, and value-added applications can contribute to more efficient use of agricultural resources and reduction of processing waste. This aligns with broader industry efforts to develop resource-efficient food production systems.
What are the key industry trends?
The market is moving toward higher-value applications and improved processing technologies. Advances in processing are helping manufacturers enhance wheat bran's sensory characteristics, functional performance, stability, and digestibility, enabling its incorporation into a wider range of products.
Digital technologies are also becoming increasingly relevant to milling and ingredient production. Artificial intelligence (AI), Internet of Things (IoT), automation, and digital traceability systems can improve production monitoring, supply-chain visibility, quality control, and operational efficiency.
Another emerging trend is the expansion of wheat bran into functional foods, nutritional formulations, dietary supplements, and specialized animal nutrition. These applications allow producers to capture additional value from wheat milling streams while responding to demand for nutrient-dense ingredients.
Which regions are gaining momentum?
Asia Pacific, Europe, and North America represent important regional markets for wheat bran, supported by adoption across food, nutraceutical, and animal feed industries.
Asia Pacific benefits from its large food-processing and agricultural base, growing demand for packaged and functional foods, and expanding animal feed sector. Increasing consumer awareness of nutrition and dietary fiber is creating additional opportunities for wheat-bran-based products.
Europe has opportunities arising from established food-processing industries, demand for functional and clean-label ingredients, and growing emphasis on resource efficiency and sustainable food production.
North America is supported by demand for high-fiber foods, nutritional products, animal feed, and value-added grain ingredients. Product innovation and increasing use of functional ingredients provide opportunities for wheat bran suppliers across food and nutrition applications.
Which segment leads?
The Wheat Bran Market is segmented by form, category, and application.
By Form
Different forms serve different processing and end-use requirements. Flour and meal formats are suitable for incorporation into food formulations, while flakes and pellets have applications across food and animal nutrition.
By Category
Organic wheat bran benefits from demand for organic and clean-label ingredients, while conventional wheat bran continues to serve a broad range of food and feed applications.
By Application
Baked goods, breakfast cereals, nutritional products, and animal feed represent important application areas. Food applications are benefiting from the incorporation of wheat bran into products positioned around fiber and nutritional value, while animal feed remains an established outlet for wheat bran generated through milling.
Which companies are prominent?
The report identifies the following companies as prominent participants in the Wheat Bran Market:
These companies participate across wheat processing, milling, ingredient production, animal nutrition, and agricultural supply chains. Competitive differentiation is increasingly associated with processing capabilities, product consistency, application-specific formulations, quality control, supply-chain efficiency, and the development of higher-value wheat-bran applications. The listed companies represent the report's competitive landscape and should not be interpreted as a revenue-ranked market-share table.
What is changing through 2026 and beyond?
The wheat bran industry is gradually moving from its traditional role as a milling by-product toward a higher-value functional ingredient and nutrition resource.
Manufacturers are investing in processing technologies that can improve wheat bran's sensory profile, digestibility, functionality, and suitability for food formulations. These improvements can expand its use in mainstream consumer products rather than limiting it to conventional milling and feed applications.
At the same time, digitalization of milling operations is supporting greater traceability, quality monitoring, automation, and supply-chain efficiency. AI- and IoT-enabled systems can help producers monitor production conditions and improve consistency across batches.
The combination of nutritional demand, food innovation, and resource-efficiency objectives is creating opportunities for wheat bran suppliers to develop differentiated products for food, nutraceutical, and animal nutrition markets.
What are the major investment opportunities?
Key opportunities are emerging in functional food ingredients, advanced wheat-bran processing, animal nutrition, dietary supplements, and value-added grain utilization.
Investment in processing technologies that improve wheat bran's functional and sensory characteristics can enable entry into premium food applications. High-fiber bakery products, breakfast cereals, nutritional bars, and functional foods provide opportunities for manufacturers to develop differentiated products around digestive health and nutritional positioning.
The animal feed sector also provides an established demand base. Wheat bran can be incorporated into animal nutrition formulations, creating opportunities for processors that can provide consistent quality, nutritional specifications, and reliable supply.
Additional opportunities exist in specialty dietary supplements and functional food and beverage formulations, where consumers are increasingly interested in ingredients associated with fiber and nutritional benefits.
From a sustainability perspective, businesses that improve the valorization of wheat milling by-products can potentially create additional value from existing agricultural processing streams while supporting resource-efficiency objectives.
Anticipated Innovations and Applications
Beyond traditional milling and feed applications, wheat bran is increasingly being explored for:
These applications support the industry's transition toward higher-value, nutrition-focused, and resource-efficient product portfolios.
Market Outlook
The Wheat Bran Market is expected to maintain steady growth through 2034 as manufacturers and consumers place greater emphasis on dietary fiber, functional nutrition, sustainable resource utilization, and ingredient innovation.
Companies seeking growth in this market should focus on product functionality, processing quality, application-specific solutions, supply-chain reliability, and the ability to translate wheat bran from a conventional milling by-product into differentiated nutritional and functional ingredients.
Trending Related Reports:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean German Japanese French Chinese Italian Spanish
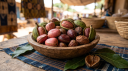
The Kola Nuts Market is expected to demonstrate steady growth during 2026–2034, supported by rising demand for natural ingredients, plant-based formulations, functional beverages, and wellness-oriented products. The Kola Nuts Market size is expected to reach US$ 2.09 Billion by 2034 from US$ 1.59 Billion in 2025. The market is estimated to record a CAGR of 3.07% from 2026 to 2034.
Kola nuts are caffeine-containing seeds derived from the kola tree and are traditionally used as flavoring agents in beverages and for their stimulating properties. Increasing consumer interest in clean-label, natural, and functional ingredients is encouraging manufacturers to explore kola nut extracts and processed forms across food, beverage, pharmaceutical, and nutraceutical applications.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00015938
The market study covers historical data from 2021 to 2024, a 2025 base year, and forecasts through 2034. The analysis evaluates market development in value terms and provides segmentation by product type, end-user industry, and region.
What is driving the market?
Growing consumer interest in natural and plant-derived ingredients is one of the principal factors supporting demand for kola nuts. Wellness trends, demand for natural energy sources, and increasing interest in functional food and beverage products are encouraging manufacturers to incorporate kola nut ingredients into new formulations.
The growing popularity of clean-label products is also influencing product development. Consumers are increasingly seeking recognizable, plant-based ingredients, while food and beverage manufacturers are exploring botanical sources of caffeine and other naturally occurring compounds.
Traditional and cultural applications are providing an additional demand base. Renewed interest in traditional remedies and natural ingredients is supporting the incorporation of kola nuts into modern food, beverage, herbal, and wellness products.
At the same time, factors such as supply-chain consistency, sustainable sourcing, quality control, regulatory requirements, and the need for standardized ingredient specifications remain important considerations for manufacturers and distributors.
Which region is expected to grow?
The Kola Nuts Market is analyzed across North America, Europe, Asia Pacific, the Middle East and Africa, and South and Central America.
Asia Pacific is anticipated to witness strong growth during the forecast period, supported by expansion of the food and beverage industry, increasing consumer awareness of natural ingredients, and growing interest in functional and wellness-oriented products.
North America and Europe represent established markets where demand is supported by functional beverages, nutraceutical innovation, clean-label product development, and consumer interest in botanical ingredients.
South America and the Middle East and Africa are also expected to contribute to market development as distribution networks expand and awareness of kola nut-based products increases. The Middle East and Africa are particularly relevant to the market because of the historical and cultural use of kola nuts in several African markets.
Which segment leads?
The market is segmented by type into:
Liquid and powder forms provide manufacturers with different options for incorporating kola nut ingredients into beverages, supplements, food products, and other formulations. Powdered kola nut can be used as an ingredient in processed products, while liquid forms and extracts can facilitate incorporation into beverage and functional formulations.
By end-user industry, the market is categorized into:
The Beverage segment represents a significant area of market demand because kola nuts have a longstanding association with beverage flavoring and naturally occurring caffeine. Growing interest in energy drinks and functional beverages is creating additional opportunities for kola nut-based ingredients.
The Nutraceutical and Pharmaceutical segments also offer growth opportunities as manufacturers investigate botanical ingredients, natural caffeine sources, and functional bioactive compounds for specialized formulations.
What are the major trends through 2034?
The market is evolving alongside broader consumer interest in wellness, natural ingredients, and functional products. Several trends are shaping product development and commercialization:
Manufacturers are also exploring processing and formulation technologies that can improve the usability, consistency, and commercial application of kola nut ingredients. Product diversification may allow suppliers to address different requirements across beverages, dietary supplements, functional foods, and other end-use categories.
What are the major investment opportunities?
Investment opportunities are emerging across ingredient processing, functional beverages, nutraceutical formulations, natural energy products, and sustainable sourcing.
Kola nut processors and ingredient suppliers can pursue opportunities by developing standardized powders, extracts, liquid formulations, and other value-added ingredients. Improving processing, quality control, traceability, and supply-chain efficiency can help manufacturers serve international customers with more consistent raw materials.
The functional beverage category represents another potential opportunity as consumers increasingly seek products positioned around energy, wellness, and natural ingredients. Kola nut-derived ingredients can potentially be incorporated into beverages where their flavor and naturally occurring caffeine characteristics align with formulation requirements.
Nutraceutical and herbal-product applications may also provide opportunities for product innovation. Manufacturers can explore formulations that combine kola nut with other botanical ingredients, subject to applicable regulatory and safety requirements.
Sustainable sourcing and transparent supply chains are becoming increasingly important. Investments in responsible procurement, supplier relationships, processing infrastructure, and traceability can help businesses establish reliable access to kola nuts while responding to growing expectations around responsible ingredient sourcing.
Which companies are prominent?
The report identifies the following companies among the key participants in the Kola Nuts Market:
These participants operate across natural ingredients, botanical products, food and beverage products, herbal formulations, and related applications. Competition is influenced by product availability, ingredient quality, processing capabilities, sourcing relationships, product diversification, distribution reach, and the ability to address growing demand for natural and functional ingredients.
The listed companies represent the competitive landscape identified in the report and should not be interpreted as a revenue-ranked market-share table.
What is changing in 2026?
In 2026, the Kola Nuts Market is increasingly aligned with the broader shift toward natural, plant-based, and functional ingredients. Food and beverage manufacturers are examining botanical alternatives and natural ingredient sources as consumers place greater emphasis on product composition and wellness attributes.
The market is also moving toward greater product diversification. Instead of relying solely on traditional applications, suppliers are exploring powders, liquid ingredients, extracts, functional beverages, supplements, and other value-added formulations.
Sourcing and supply-chain transparency are becoming increasingly relevant as manufacturers and consumers place greater emphasis on responsible procurement. Consistent quality, traceability, processing standards, and reliable availability are therefore important considerations for companies seeking to expand internationally.
What are the major challenges?
Despite its growth potential, the market faces several challenges.
Supply availability and consistency can influence the ability of manufacturers to scale production. Differences in raw-material quality, processing methods, and ingredient standardization may also affect formulation performance.
Regulatory requirements represent another consideration, particularly for products positioned as functional, pharmaceutical, or nutraceutical ingredients. Companies must ensure that product claims, formulations, labeling, and intended uses comply with applicable regulations in individual markets.
Consumer awareness remains uneven outside regions where kola nuts have established cultural or commercial applications. Greater education, product innovation, and distribution expansion may therefore be necessary to broaden adoption in new markets.
Related Reading / Reports
Additional research covering related nut and natural-ingredient markets includes:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The Seaweed Products Market was valued at US$ 11.09 billion in 2025 and is projected to reach US$ 13.03 billion by 2034, registering a CAGR of 1.80% during 2026–2034. The market encompasses products derived from red, brown, and green seaweed and includes alginate, agar, carrageenan, seaweed meal, and seaweed fertilizers.
Demand is being supported by growing interest in sustainable resources, health and wellness products, functional food ingredients, agricultural applications, and emerging seaweed-based packaging and personal-care solutions.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00013942/
What is driving the market?
Sustainability, changing consumer preferences, and the expanding use of seaweed-derived ingredients across food, agriculture, pharmaceuticals, and other industries are key factors supporting market development. Seaweed is increasingly viewed as a versatile biological resource that can provide functional ingredients while supporting broader sustainability objectives.
The health and wellness trend is creating demand for nutrient-rich seaweed foods and snacks. Seaweed-based ingredients are also used for functional and formulation purposes, including hydrocolloids such as alginate, agar, and carrageenan. At the same time, interest in renewable and lower-impact materials is encouraging exploration of seaweed for packaging and other applications. The Insight Partners identifies sustainable growth, seaweed superfoods, and eco-friendly packaging innovations among the principal market growth drivers.
The market is also benefiting from technological developments that enable seaweed to be processed into higher-value products. Increasing awareness of the potential benefits of seaweed-derived ingredients is encouraging companies to expand product portfolios and pursue applications beyond traditional food uses.
Which region leads?
The report analyzes the market across North America, Europe, Asia Pacific, South and Central America, and the Middle East and Africa, with country-level coverage including the US, Canada, Mexico, China, India, Japan, Australia, the UK, Germany, France, Italy, Russia, Brazil, Argentina, South Africa, Saudi Arabia, and the UAE.
Asia Pacific represents an important market because of the region's established seaweed cultivation and processing activities and its large food and agricultural markets. China, India, Japan, and Australia are specifically included in the report's country-level analysis. Growing applications in food, feed, agriculture, and industrial ingredients provide multiple channels for market development. North America is also a significant market, with the United States identified by The Insight Partners as a key market. Demand is linked to sustainability initiatives, health and wellness trends, food applications, and emerging uses of seaweed-derived materials. The Insight Partners
Europe and other regions are likewise covered in the report, with opportunities influenced by sustainable-product demand, food innovation, agricultural applications, and development of new seaweed-based products.
Which segment leads?
The market is segmented by source, product type, and end-use industry. By source, the report covers red seaweed, brown seaweed, and green seaweed. By product type, it analyzes alginate, agar, carrageenan, seaweed meal, and seaweed fertilizers. End-use industries include food, pharmaceuticals, feed, and agriculture.
Food is a major application area because seaweed is increasingly incorporated into snacks, functional foods, ingredients, and other food products. The growing consumer interest in nutrient-rich and alternative food products is creating opportunities for seaweed-based offerings. The Insight Partners
Among product categories, alginate, agar, and carrageenan remain important because of their functional properties and established use as hydrocolloid ingredients. Meanwhile, seaweed meal and seaweed fertilizers provide opportunities in animal feed and agriculture as interest grows in biological and sustainable inputs.
What is changing in 2026?
The seaweed products industry is moving beyond traditional food applications toward a broader multi-industry utilization model. Companies are exploring seaweed-derived ingredients and materials for sustainable packaging, food alternatives, cosmetics and personal care, agriculture, feed, and other applications.
One notable trend is the development of seaweed-based sustainable packaging solutions. Interest in alternatives to conventional packaging materials is encouraging research and commercialization efforts involving seaweed-derived materials.
At the consumer level, nutrient-rich food alternatives and seaweed snacks are receiving increasing attention as health-conscious consumers seek functional and plant-based products. The Insight Partners also identifies eco-friendly cosmetics and personal-care products as an emerging application area.
What are the major investment opportunities?
The market presents opportunities across seaweed cultivation, processing, functional ingredients, food products, agricultural inputs, sustainable packaging, and personal care.
One important opportunity is the expansion of sustainable seaweed farming. Investment in cultivation technologies, processing capacity, quality control, and supply-chain infrastructure can support a more consistent supply of raw material as downstream applications expand.
Seaweed-based food and snacks represent another opportunity as consumers increasingly seek nutrient-rich and alternative food products. Product development can extend beyond traditional seaweed consumption into functional foods, ingredients, beverages, and convenient snack formats.
There are also opportunities in seaweed-derived hydrocolloids, particularly alginate, agar, and carrageenan, where established industrial applications provide a foundation for continued product development. Agricultural applications such as seaweed meal and fertilizers offer another avenue for growth as producers explore biological and sustainable inputs.
Emerging opportunities include seaweed-based packaging and biomaterials, as well as cosmetics and personal-care formulations. Investors and companies can therefore assess opportunities across both established ingredient markets and newer higher-value applications.
Which companies are prominent?
The report identifies DuPont, Cargill Inc., CP Kelco, KIMICA Corporation, W Hydrocolloids Inc., Connemara Seaweed Company, Maine Seaweed LLC, Irish Seaweeds, SHIDAI MARINE BIOTECHNOLOGY CO., LTD., and Acadian Seaplants Limited among the companies profiled in its competitive landscape.
These participants operate across areas including seaweed-derived ingredients, hydrocolloids, seaweed cultivation, processing, food applications, agricultural products, and biotechnology. Competition is increasingly shaped by product innovation, processing capabilities, supply-chain access, application development, and the ability to commercialize seaweed-derived products across multiple industries.
The list represents the report's profiled market participants and competitive landscape rather than a revenue-ranked market-share table.
Market Outlook 2026–2034
The seaweed products industry is expected to develop through a combination of established applications and emerging higher-value uses. The global market is forecast to increase from US$ 11.09 billion in 2025 to US$ 13.03 billion by 2034, reflecting a 1.80% CAGR over 2026–2034. The Insight Partners
The addressable market is expanding as seaweed moves from traditional food and hydrocolloid applications into sustainable packaging, functional foods, agriculture, feed, cosmetics, and other biomaterial applications. Companies that can combine reliable seaweed sourcing, efficient processing, product quality, regulatory compliance, and application-specific innovation will be positioned to participate across these expanding value chains.
Related Reading / Reports
Explore additional market research covering sustainable food ingredients, biomaterials, agricultural inputs, and related applications:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The Tallow Market was valued at US$7.65 billion in 2023 and is projected to reach US$11.41 billion by 2031, registering a CAGR of 5.1% during 2023–2031. The market is expanding as tallow finds broader applications across biofuels, animal nutrition, personal care and cosmetics, food and beverages, lubricants, soaps, detergents, and other industrial uses.
Growth is supported by the increasing utilization of animal-derived fats as renewable feedstocks, rising demand for biofuels, expanding animal nutrition applications, and growing consumer interest in natural ingredients. The Insight Partners
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00039270/
What is driving the market?
The broad application base of tallow and its increasing use in animal nutrition and biofuel production are key drivers of market growth. Tallow is a rendered animal fat that can be sourced from beef, sheep, camels, horses, buffaloes, lambs, and other animals. It is available in edible, inedible, and technical grades, allowing it to serve diverse food, feed, personal care, chemical, and industrial applications. The Insight Partners
The biofuel industry is becoming an increasingly important demand center. Tallow can be used as a feedstock for biodiesel and other renewable fuels, offering an alternative to conventional fossil-based feedstocks. Growing efforts to reduce dependence on fossil fuels, lower greenhouse-gas emissions, and expand renewable fuel consumption are supporting demand for rendered animal fats. The Insight Partners
Animal nutrition is another important growth area. Tallow provides a concentrated source of energy and is used in poultry feed, livestock nutrition, pet food, and other feed applications. Increasing pet adoption and greater awareness of pet nutrition are also contributing to demand for animal fats in pet-food formulations. The Insight Partners
At the same time, the use of tallow in personal care and cosmetics is gaining attention as consumers increasingly seek products positioned around natural and animal-derived ingredients. The Insight Partners identifies preference for beauty products made from natural ingredients as a key future market trend. The Insight Partners
Which region leads?
North America leads the global tallow market, accounting for approximately 58.2% of the market in 2023. The region benefits from established meat-processing and rendering industries, significant demand for animal-feed ingredients, and growing utilization of tallow in biodiesel and renewable-fuel applications. The Insight Partners
The region's strong livestock and meat-processing base provides a consistent supply of rendered animal fats, while demand from fuel, food and beverages, personal care and cosmetics, and lubricants supports downstream consumption.
The United States is projected to grow at a 4.6% CAGR during the forecast period. Meanwhile, Asia Pacific is expected to be the fastest-growing major region, with a projected 6.5% CAGR, creating opportunities as industrialization, livestock production, consumer-product manufacturing, and demand for renewable fuels expand. The Insight Partners
Which segment leads?
By source, the Beef segment dominates the market, accounting for approximately 83.5% of the market in 2023. Beef-derived tallow benefits from the scale of the global cattle and meat-processing industries and its broad suitability for food, feed, biofuel, personal care, and industrial applications. The Insight Partners
By end-use industry, the market is segmented into Food & Beverages, Personal Care & Cosmetics, Lubricants, Biofuel, Animal Nutrition, and Others. The report identifies Biofuel as the largest end-use segment in 2023, reflecting the increasing use of tallow as a renewable feedstock. The Insight Partners
Personal Care & Cosmetics is identified as the fastest-growing end-use segment, with a projected 6.4% CAGR through the forecast period. Rising consumer preference for natural ingredients and the development of tallow-based beauty and personal-care products are supporting this growth. The Insight Partners
Which companies are prominent?
The report identifies Cargill Inc., Dalian Daping Oil Chemicals Co. Ltd, ECSA Chemicals SA, Minerva SA, NH Foods Australia Pty Ltd, Craig Mostyn Group, Tassie Tallow, Leo Group Ltd, Maine Tallow Company, and Pridham Pty Ltd among the key market participants. The Insight Partners
Other companies profiled in the broader competitive landscape include Targray Technology International Inc., AGRI INTERNATIONAL, Baker Commodities, Inc., Dalian Daping Oil Chemicals Co. Ltd, HRR Enterprises, Inc., and KRV Yağ ve Kemik San. Tic. A.Ş. The Insight Partners
Competition is shaped by rendering capacity, feedstock sourcing, product quality, geographic reach, downstream integration, and the ability to serve diverse applications ranging from biofuels and animal nutrition to personal care, lubricants, and food products.
The list reflects the report's competitive landscape and should not be interpreted as a revenue-ranked market-share table.
What is changing in 2026?
The tallow market is increasingly being influenced by the transition toward renewable feedstocks, natural ingredients, and higher-value utilization of animal byproducts. Tallow is moving beyond its traditional applications in soaps, candles, animal feed, and industrial products as demand grows for renewable fuel feedstocks and natural-ingredient formulations.
Biofuel demand is particularly important because tallow can serve as a feedstock for biodiesel and renewable fuels. Increasing efforts to reduce fossil-fuel dependence and carbon emissions are encouraging greater utilization of waste and residue-based feedstocks. The Insight Partners
At the same time, manufacturers are exploring higher-value applications in cosmetics and personal care. This creates opportunities for refined and specialty tallow products that can meet specific formulation, quality, purity, and performance requirements.
The market is therefore shifting from simply processing an animal byproduct toward maximizing the commercial value of rendered fats across multiple end-use industries.
What are the major investment opportunities?
The strongest opportunities lie in rendering infrastructure, renewable fuels, animal nutrition, specialty personal-care ingredients, and supply-chain integration.
Investment in modern rendering and processing facilities can improve the recovery, purification, storage, and commercialization of animal fats. Companies with reliable access to slaughterhouse and meat-processing feedstocks can benefit from more consistent raw-material availability.
The biofuel segment offers substantial strategic potential as demand for renewable and lower-carbon fuel feedstocks expands. Tallow's role as a feedstock for biodiesel and renewable fuels provides opportunities for renderers, fuel producers, traders, and integrated meat-processing companies. The Insight Partners
Animal nutrition represents another attractive opportunity. Tallow's high energy density makes it useful in poultry, livestock, and pet-food applications, while continued growth in pet ownership supports demand for animal-based nutritional ingredients.
The personal care and cosmetics market offers a higher-value opportunity, particularly for companies able to develop refined tallow ingredients that meet formulation and quality requirements. With this segment projected to grow at 6.4% annually, companies positioned around natural-ingredient beauty products may capture above-market growth. The Insight Partners
Asia Pacific also presents attractive expansion potential, with the region projected to record a 6.5% CAGR. Investors should prioritize businesses with secure feedstock access, efficient rendering capabilities, strong downstream partnerships, and the flexibility to serve both commodity and specialty applications. The Insight Partners
Related Reading / Reports
Explore additional market research covering animal-derived ingredients, renewable feedstocks, biofuels, and related food, feed, and personal-care applications:
What is driving the market?
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The Art Supplies Market was valued at US$ 16.90 Billion in 2025 and is projected to reach US$ 24.05 Billion by 2034, registering a CAGR of 4.00% during 2026–2034. The market is expanding as educational institutions, households, hobbyists, commercial designers, professional artists, and independent creators maintain demand for drawing, painting, coloring, writing, and craft-related products.
Growth is supported by creative learning initiatives, recurring school procurement, premiumization among hobbyists and professionals, expanding e-commerce, and the increasing integration of traditional art products into creator and digital-content workflows. The Insight Partners
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00028440
What is driving the market?
Creative learning, school procurement, hobby participation, and the expansion of independent creator communities are the principal growth drivers. Educational institutions continue to generate recurring demand for products such as drawing paper, pencils, colors, erasers, paints, and other classroom supplies. The market also benefits from increased participation in hobbies, journaling, DIY activities, illustration, and other creative pursuits.
Premiumization is becoming increasingly important. Professional artists, illustrators, designers, calligraphers, and independent creators are showing greater willingness to purchase higher-quality pencils, pigment markers, brushes, sketch pads, papers, and specialty colors. Product attributes such as pigment quality, lightfastness, smooth application, archival performance, ergonomics, and durability are increasingly influencing purchasing decisions. The Insight Partners
The market is also becoming more omnichannel. Retailer-exclusive launches, direct-to-consumer stores, marketplaces, and social-media-led product discovery are changing how consumers find and replenish art supplies. Brands are increasingly combining physical retail distribution with online merchandising, seasonal collections, creative kits, and creator-focused product ranges.
Which region leads?
North America leads the global art supplies market, accounting for an estimated 31%–34% share in 2025. The region is projected to grow at a CAGR of 3.6%–4.1% during 2026–2034. Strong school procurement, established specialty retail networks, household participation in crafts, and demand for branded and premium products support the region's leading position. The Insight Partners
The United States represents approximately 78%–82% of the North American market, supported by classroom purchasing, back-to-school retail cycles, hobby and craft consumption, and demand from designers, architects, illustrators, and content creators.
Europe held approximately 26%–29% of the global market in 2025 and is expected to grow at a 3.2%–3.8% CAGR through 2034. Germany, the UK, France, Italy, and Spain are important markets, with demand supported by professional art education, established brands, specialty retail, and growing preference for certified wood, low-toxicity materials, recyclable packaging, and durable products.
Asia Pacific accounted for approximately 25%–28% of the market in 2025 and is the fastest-growing major region, with a projected 4.6%–5.3% CAGR. China leads regional consumption, while Japan and South Korea have strong premium writing and illustration markets. India and Australia are also contributing through education expansion, household creativity, organized retail, and increasing access to branded products. The Insight Partners
Which segment leads?
By product type, the segment accounts for an estimated 61%–65% market share in 2025 and is projected to grow at a 3.8%–4.3% CAGR through 2034. Its strength reflects frequent replacement and replenishment cycles across education, home, commercial, and professional applications. The category includes paints, drawing paper/pads, pencils, pens, highlighters, brushes, erasers, and colors. The Insight Partners
Pencils, drawing paper/pads, paints, pens, and colors remain important because they serve multiple consumer groups ranging from schoolchildren and hobbyists to professional artists and designers. Demand is increasingly influenced by product performance, safety, sustainability, ergonomics, and specialty applications.
By end user, education and home users represent important volume-generating groups, while Independent Professionals are emerging as a high-growth segment. Independent Professionals represented approximately 10%–13% of the market in 2025 and are forecast to grow at a 5.0%–5.7% CAGR through 2034, supported by creator monetization, commissions, illustration, social-media content creation, and demand for premium tools. The Insight Partners
What is changing in 2026?
The art supplies market is moving beyond traditional school and stationery demand toward a broader creative ecosystem that connects education, hobbies, professional art, e-commerce, and digital content creation.
Sustainability is increasingly becoming a purchasing criterion. Schools, retailers, and professional users are showing greater interest in certified wood, recycled paper, refillable pens, recyclable packaging, low-toxicity formulations, and durable products. Manufacturers that can demonstrate responsible sourcing and reduce material waste may gain an advantage in institutional and premium markets. The Insight Partners
Another important shift is the emergence of hybrid digital–analog creative workflows. Artists and creators increasingly draw or paint physically and then scan, photograph, upload, teach, or monetize their work through digital platforms. This is creating demand for high-pigment pencils, fineliners, brush pens, marker-compatible paper, and portable artist kits that perform well both physically and when captured digitally.
What are the major investment opportunities?
The strongest opportunities lie in premium artist supplies, localized education packs, sustainable materials, creator-focused products, and omnichannel distribution.
Localized school and home-learning kits represent an attractive opportunity in emerging urban markets. Manufacturers can combine pencils, colors, erasers, paper, paints, and other products into curriculum-oriented packs with localized pricing, pack sizes, and language support. Partnerships with schools, distributors, and e-commerce platforms can strengthen distribution and reduce stockout risks.
Premium specialist ranges offer another attractive opportunity. Products designed for illustrators, calligraphers, manga artists, designers, journaling enthusiasts, and professional hobbyists can command higher margins than standardized school products. Strong opportunities exist around pigment quality, color consistency, archival performance, ergonomic design, portability, and refill systems.
Sustainable products also offer room for differentiation through certified wood, recycled paper, refillable writing instruments, low-toxicity formulations, and reduced-plastic packaging.
Asia Pacific offers particularly attractive expansion potential because of its combination of population scale, education growth, rising incomes, organized retail development, and expanding creator communities. Investors and manufacturers should prioritize products that combine affordability with quality while adapting pack sizes and price points to local markets.
Overall, the competitive landscape is shifting from simple volume-driven stationery sales toward segmented creative ecosystems in which education, home creativity, professional art, sustainability, premiumization, and digital creator culture increasingly overlap. The Insight Partners
Which companies are prominent?
The report identifies Faber-Castell AG, Crayola LLC, Maped SAS, Pacon Corporation, Pilot Corporation, Newell Brands Inc., STAEDTLER SE, Mitsubishi Pencil Co., Ltd., Pelikan Group GmbH, and Hindustan Pencils Pvt. Ltd. as key companies analyzed in the competitive landscape. The Insight Partners
These companies compete across professional art materials, educational products, writing instruments, pencils, colors, markers, paper products, and mass-market creative supplies. Competitive differentiation increasingly depends on product quality, safety, sustainability, brand reputation, distribution reach, innovation, price positioning, and the ability to serve distinct consumer groups.
The company list represents the report's competitive landscape and should not be interpreted as a revenue-ranked market-share table.
Related Reading / Reports
Explore additional research covering consumer goods, stationery, sustainable materials, and adjacent markets:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact US:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The Animal Feed Enzymes Market was valued at US$1.28 billion in 2025 and is projected to reach US$2.13 billion by 2034, registering a CAGR of 5.79% during 2026–2034. The market is expanding as livestock producers and feed manufacturers increasingly use enzymes to improve nutrient utilization, enhance feed conversion, reduce feed costs, and support more sustainable animal production.
Growth is supported by rising feed-cost pressure, greater use of plant-based feed ingredients, nutrient-excretion reduction requirements, and increasing adoption of precision nutrition strategies.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00016500/
What is driving the market?
Feed-cost optimization, sustainability requirements, and the need for improved nutrient utilization are the principal growth drivers. Feed represents a major operating cost for poultry, swine, and aquaculture producers, increasing demand for additives that can extract more usable nutrients from cereals, oilseed meals, and other feed ingredients.
Phytase helps release phosphorus bound in phytate, reducing dependence on inorganic phosphate supplements and improving phosphorus utilization. Carbohydrases improve energy utilization by breaking down non-starch polysaccharides in grains and by-products, while proteases improve protein and amino-acid utilization. These benefits allow producers to optimize formulations while maintaining animal performance.
Sustainability is becoming increasingly important. Livestock producers are under pressure to reduce phosphorus and nitrogen losses, manage nutrient excretion, and improve resource efficiency. Enzyme solutions are therefore increasingly evaluated not only for their direct feed-cost benefits but also for their contribution to environmental performance.
The growing use of plant-based feed ingredients is another important factor. As producers use more soybean meal, canola meal, grains, and other alternative raw materials, enzymes can help improve digestibility and manage variability in feed quality. This is particularly relevant in aquaculture, where formulators are increasingly replacing fishmeal with plant-based proteins.
Which region leads?
Asia Pacific leads the market, accounting for an estimated 34%–38% share in 2025, and is also among the fastest-growing regions with a projected CAGR of 6.2%–7.0% through 2034. China represents the largest regional demand market, supported by industrial feed production and modernization of pig production. India and Southeast Asia are also increasing enzyme adoption in poultry and compound-feed production. Aquaculture represents an additional growth opportunity as producers use enzymes to improve plant-protein digestibility.
North America accounted for an estimated 24%–28% share in 2025 and is projected to grow at a 5.1%–5.7% CAGR. The region benefits from large integrated poultry and swine operations, advanced feed-milling infrastructure, established nutrition practices, and increasing focus on feed efficiency and nutrient management. The US represents approximately 74%–78% of North American revenue.
Europe held an estimated 20%–24% share in 2025 and is forecast to grow at 4.8%–5.4% CAGR. Germany, France, Spain, Italy, and the UK are important markets, with adoption supported by environmental requirements, feed-quality standards, nutrient-efficiency objectives, and established poultry and swine industries.
The Middle East & Africa market is projected to grow at approximately 5.5%–6.2% CAGR through 2034. Saudi Arabia, the UAE, and South Africa represent important markets, with demand supported by poultry and dairy production, food-security initiatives, and the need to improve feed efficiency under challenging input-cost and climatic conditions.
Which segment leads?
Phytase is the leading enzyme type, representing an estimated 36%–42% of market revenue in 2025 and projected to grow at approximately 5.3%–6.0% CAGR. Its leading position is supported by its ability to improve phosphorus availability, reduce inorganic phosphate requirements, lower feed costs, and support nutrient-management objectives, particularly in poultry and swine production.
Carbohydrases are increasingly important because they improve energy utilization from grains and other feed ingredients. Their value increases where wheat, barley, corn, and alternative raw materials exhibit variable digestibility.
Protease represented an estimated 18%–23% share in 2025 and is identified as a high-growth segment, with an expected 6.4%–7.2% CAGR. Growth is supported by high-protein poultry and swine diets, soybean-meal variability, and increasing use of plant proteins in aquaculture feed. TThe Insight Partners
By livestock, Poultry is the largest application category, supported by large-scale compound-feed production and widespread phytase adoption. Swine represents another major application, while ruminant use is more selective. Aquatic animals are an emerging high-potential segment, particularly as aquafeed manufacturers increase the use of plant proteins and seek improved digestibility.
By source, microorganism-derived enzymes dominate because microbial fermentation provides scalable production, consistent activity, and flexibility to engineer enzymes for thermostability and species-specific performance. Plant-derived enzymes remain niche, while animal-derived enzymes have more limited applications because of cost, scalability, and consistency considerations. TThe Insight Partners
By form, dry enzymes remain widely used because they are convenient for premixes, compound-feed manufacturing, handling, and storage. Liquid enzymes are gaining importance in post-pelleting applications, where they can help protect enzyme activity from high processing temperatures and enable more flexible dosing.
Which companies are prominent?
The report identifies Adisseo, Advanced Enzyme Technologies Limited, BASF SE, BioResource International, Inc., Cargill, Incorporated, DSM-Firmenich, IFF, Elanco Animal Health Incorporated, ENMEX, and Novonesis A/S among the key companies analyzed in the market.
These companies compete through enzyme innovation, microbial fermentation capabilities, feed-formulation expertise, technical services, distribution networks, species-specific solutions, and performance validation. Competitive positioning is increasingly shifting from individual enzyme products toward broader precision-nutrition platforms that can combine enzymes with other feed additives and formulation technologies. TThe Insight Partners
The competitive landscape is moderately consolidated, with major suppliers investing in thermostable enzymes, customized blends, microbial strains, and technical support. Suppliers that can demonstrate measurable improvements in feed conversion, nutrient release, production economics, and sustainability are increasingly positioned to differentiate beyond price.
What is changing in 2026?
The animal feed enzymes market is moving from conventional single-enzyme supplementation toward precision enzyme solutions tailored to animal species, feed composition, raw-material quality, and processing conditions. Feed manufacturers are increasingly combining phytase, xylanase, amylase, beta-glucanase, protease, and other enzymes to target specific nutritional requirements.
Manufacturers are also investing in thermostable enzymes and post-pelleting delivery systems. High temperatures during feed pelleting can reduce enzyme activity, increasing demand for improved microbial strains, protective coatings, and liquid application technologies that maintain predictable enzyme performance through processing, storage, and feeding.
The market is also becoming increasingly data-driven. Suppliers are combining enzyme products with technical services, feed analysis, formulation software, and performance data to demonstrate improvements in feed conversion, phosphorus utilization, nitrogen efficiency, and overall production economics.
What are the major investment opportunities?
The strongest opportunities lie in precision enzyme blends, microbial fermentation, thermostable enzyme technologies, aquaculture feed solutions, and integrated sustainability programs for poultry and swine producers.
Aquaculture offers particularly attractive potential in Asia Pacific. As shrimp, tilapia, carp, and marine-fish producers increase their reliance on formulated feeds and replace portions of fishmeal with plant proteins, specialized protease and carbohydrase solutions can improve digestibility, feed conversion, and nutrient utilization.
Investment opportunities also exist in advanced microbial strains and fermentation capacity. Improvements in enzyme stability, activity, scalability, and resistance to processing conditions can support premium products and reduce variability for high-throughput feed mills.
Large poultry and swine integrators represent another important opportunity. Suppliers can move beyond commodity enzyme sales by integrating products with technical services, formulation support, sustainability metrics, and production data. Demonstrating lower phosphorus and nitrogen losses alongside measurable feed-efficiency gains can strengthen long-term customer relationships.
Asia Pacific offers particularly attractive expansion potential because of its large livestock and aquaculture industries, increasing compound-feed production, and continued adoption of plant-based feed ingredients. Investors should prioritize technologies that combine validated animal-performance benefits, processing stability, production scalability, cost competitiveness, and measurable sustainability outcomes.
Related Reading / Reports
Explore additional research covering animal nutrition, feed additives, sustainable livestock production, and the broader transition toward precision animal nutrition:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The animal protein market is witnessing substantial growth driven by increasing consumer awareness regarding protein rich diets and rising demand for high quality nutritional products. The Animal Protein Market size is projected to reach US$ 79.49 billion by 2034 from US$ 51.02 billion in 2025. The market is anticipated to register a CAGR of 5.70% during the forecast period 2026-2034.
Animal proteins derived from sources such as dairy, eggs, fish, and meat play a vital role in human nutrition, offering essential amino acids that are not easily obtained from plant based alternatives.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00012877/
The market is also benefiting from expanding applications in food and beverages, pharmaceuticals, and animal feed industries. Growing urbanization and changing dietary habits across emerging economies continue to fuel demand, making animal protein a key segment in the global nutrition industry.
This steady growth trajectory is supported by technological advancements in protein extraction and processing methods, which enhance product quality and functionality. Additionally, increasing investments in research and development activities by key industry players are contributing to the introduction of innovative protein solutions tailored to meet diverse consumer preferences.
One of the major drivers of the animal protein market is the growing demand for functional and fortified food products. Consumers are increasingly seeking foods that offer additional health benefits beyond basic nutrition. Animal proteins are widely used in dietary supplements, sports nutrition, and clinical nutrition products due to their high bioavailability and effectiveness. The rise in fitness awareness and active lifestyles has further boosted the demand for protein enriched foods and beverages, particularly among younger populations and athletes.
In addition, the food processing industry is expanding rapidly, especially in developing regions, which is creating significant opportunities for animal protein manufacturers. Processed foods, ready to eat meals, and convenience products often incorporate animal proteins to enhance taste, texture, and nutritional value. The dairy industry also plays a crucial role, with products such as whey protein and casein gaining popularity across global markets. Increasing consumption of dairy based protein products is further contributing to the growth of the market.
However, the market faces certain challenges that could hinder its growth. Rising concerns about environmental sustainability and animal welfare have led to increased scrutiny of animal based products. Consumers are gradually exploring alternative protein sources, including plant based and lab grown proteins. Regulatory frameworks related to food safety and quality standards also pose challenges for manufacturers, requiring continuous compliance and investment in quality assurance processes.
Despite these challenges, the animal protein market continues to evolve with innovations aimed at improving sustainability and efficiency. Companies are adopting advanced technologies such as precision fermentation and improved feed formulations to enhance protein yield while minimizing environmental impact. Strategic collaborations and partnerships are also becoming common, enabling companies to expand their product portfolios and geographic reach.
Animal Protein Market Segmentation
Source
Form
Application
Geography
Regionally, North America and Europe remain prominent markets due to high consumer awareness and established food processing industries. Meanwhile, Asia Pacific is expected to witness significant growth during the forecast period, driven by increasing population, rising disposable incomes, and changing dietary preferences. Countries such as China and India are emerging as key markets, offering lucrative opportunities for industry players.
Market leaders and key company profiles
• Amco Proteins
• Arla Foods
• Bovogen Biologicals Pty Ltd.
• Cargill, Incorporated
• Cooke Inc.
• Gelita AG
• Kerry Group
• Royal FrieslandCampina N.V.
• Saputo Inc.
• Valley Proteins, Inc.
The competitive landscape of the animal protein market is characterized by the presence of several global and regional players focusing on product innovation, mergers, and acquisitions. Companies are actively investing in expanding their production capacities and enhancing their supply chain networks to meet the growing demand. With continuous advancements and strategic initiatives, the market is poised for steady growth throughout the forecast period.
Trending Related Reports:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish
The animal feed micronutrients market was valued at US$ 1.98 Billion in 2025 and is projected to reach US$ 2.94 Billion by 2034, expanding at a CAGR of 4.49% during 2026 to 2034. The market is benefiting from the growing emphasis on animal productivity, nutrient efficiency, feed conversion optimization, and trace mineral supplementation across commercial livestock production systems.
Micronutrients such as zinc, copper, manganese, iron, and boron are increasingly incorporated into animal feed formulations to support animal health, immunity, reproductive performance, metabolic functions, and growth. As livestock production becomes more intensive, feed manufacturers and producers are placing greater emphasis on scientifically formulated nutrition solutions.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00016576/
Key Factors Driving Market Expansion
One of the major factors supporting the animal feed micronutrients market is rising global demand for animal protein. Increasing consumption of meat, eggs, and dairy products is encouraging higher poultry, dairy, swine, and beef production. This expansion requires balanced feed formulations that can support animal health while improving feed conversion and production efficiency.
Precision livestock nutrition is another important growth driver. Feed manufacturers are increasingly adopting digital monitoring systems and nutritional models that allow micronutrient supplementation to be adjusted according to animal species, age, production stage, and environmental conditions. These approaches can help optimize nutrient utilization, reduce feed costs, and minimize nutrient losses.
Regulatory emphasis on sustainable livestock production is also influencing product development. Producers are seeking micronutrient solutions with improved bioavailability that can help increase nutrient utilization and reduce environmental discharge.
Segmentation Analysis
Type
The Type segment is projected to expand at a CAGR of 4.3–4.9% during 2026–2034. The market scope within this segment continues to broaden as livestock producers seek targeted mineral supplementation to enhance immunity, growth, fertility, and feed efficiency. Product innovation increasingly focuses on improving absorption rates and reducing environmental discharge through advanced mineral delivery systems.
Livestock
The Livestock segment is expected to grow at a CAGR of 4.7–5.3% during 2026–2034. Demand varies according to production intensity, species-specific nutrition requirements, and commercial feed penetration rates. Rising consumption of animal protein and broader adoption of scientifically formulated diets continue to support long-term segment expansion.
Emerging Trends and Competitive Landscape
A key trend in the animal feed micronutrients market is the transition toward organic and chelated mineral solutions. These products are designed to provide improved bioavailability and more efficient nutrient utilization. Data-driven feed formulation platforms are also expected to gain importance as producers increasingly combine farm performance data, health indicators, environmental conditions, and nutritional requirements.
The market is moderately concentrated, with major companies competing through product innovation, technology, technical services, and distribution capabilities. Companies analyzed by The Insight Partners include BASF SE, Novus International, Inc., Purina Animal Nutrition LLC, AG Solutions, Beachport Corporation Pty Ltd, Zinpro Corporation, Bluestar Adisseo Company, Prathista Industries Ltd, Dallas Keith Limited, and Archer Daniels Midland Company.
Overall, continued livestock commercialization, rising animal protein consumption, precision nutrition, and demand for sustainable feed solutions are expected to support steady expansion of the animal feed micronutrients market through 2034.
Trending Related Reports:
About Us:
The Insight Partners is a one stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Device, Technology, Media and Telecommunications, Chemicals and Materials.
Contact Us
If you have any queries regarding this report or require additional information, please contact us:
The Insight Partners
Email: sales@theinsightpartners.com
Phone: +1-646-491-9876
Website: https://www.theinsightpartners.com/
Also Available in : Korean | German | Japanese | French | Chinese | Italian | Spanish