


Automotive Brake Pad adoption is supported by increasing awareness of vehicle maintenance and the importance of replacing worn braking components to maintain reliable stopping performance.
The Automotive Brake Pad Market was valued at US$ 2,821.77 million in 2023 and is projected to reach US$ 4,034.09 million by 2031, registering a CAGR of 4.6% during 2023–2031. The market is expanding as vehicle production, road transportation, replacement demand, and advancements in braking technologies support sustained requirements for reliable friction materials. Increasing emphasis on vehicle safety, braking performance, durability, noise reduction, and environmentally conscious material formulations is also influencing product development across passenger and commercial vehicle applications.
What is driving the market?
Vehicle production and the growing global vehicle parc are key factors supporting demand for automotive brake pads. As the number of vehicles in operation increases, the replacement market creates recurring demand because brake pads are wear components that require periodic inspection and replacement. Rising urban mobility, commercial transportation, logistics activity, and vehicle usage further contribute to replacement requirements.
Safety regulations and consumer expectations are also encouraging manufacturers to improve braking performance. Brake pad producers are focusing on friction stability, thermal resistance, wear characteristics, noise reduction, and consistent stopping performance under different operating conditions. These requirements are particularly important for passenger cars, commercial vehicles, and high-performance applications where braking systems must operate reliably under varying loads and temperatures.
The transition toward low-metallic, ceramic, and other advanced friction-material formulations is changing product development. Manufacturers are working to reduce undesirable emissions and dust while maintaining braking efficiency and durability. Raw material prices, formulation complexity, regulatory requirements, and the need to balance braking performance with cost remain important considerations for market participants.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPTE100000885
Which region leads?
Asia Pacific represents a major market for automotive brake pads, supported by vehicle manufacturing capacity, expanding automotive production, increasing vehicle ownership, and a large replacement market. China, Japan, India, and South Korea have substantial automotive manufacturing ecosystems and continue to support demand for braking components across passenger and commercial vehicles.
Europe remains an important market due to its established automotive industry, stringent vehicle safety requirements, mature aftermarket, and emphasis on advanced vehicle technologies. Demand is supported by replacement requirements as well as continued innovation in friction materials and braking systems.
North America also represents a significant market, driven by a large installed vehicle base, substantial light-duty and commercial vehicle usage, and established aftermarket distribution networks. The region's replacement market provides recurring demand for brake pads, while manufacturers continue to focus on product performance, durability, and compliance with applicable automotive requirements.
Which segment leads?
By Vehicle Type
By Product Type
By Material Type
Which companies are prominent?
These companies participate across automotive component manufacturing, electrical and connectivity systems, and related automotive supply-chain activities. Competition increasingly depends on product reliability, manufacturing efficiency, technological development, quality management, customer relationships, and the ability to meet evolving automotive industry requirements. The listed companies reflect the competitive landscape identified for the market and are not presented as a revenue-ranked market-share table.
What is changing in 2026?
The automotive brake pad market is increasingly influenced by developments in vehicle electrification, advanced braking systems, sustainability requirements, and changing vehicle architectures. Electric vehicles introduce different braking characteristics because regenerative braking can reduce reliance on conventional friction braking during certain driving conditions. This is encouraging manufacturers to consider formulations and product characteristics suited to lower-frequency but still safety-critical friction braking.
At the same time, automakers and component suppliers are paying greater attention to brake dust, material composition, noise, vibration, and environmental performance. Research and development efforts are therefore moving toward friction materials that can maintain consistent stopping performance while addressing emissions and comfort considerations.
The aftermarket remains an important source of demand. Vehicle owners, repair workshops, distributors, and fleet operators increasingly seek brake pads that provide dependable performance, predictable wear, and compatibility with specific vehicle models. Digital vehicle diagnostics and condition-monitoring technologies may also support more data-driven maintenance decisions over time.
What are the major investment opportunities?
Major opportunities exist in advanced friction materials, aftermarket distribution, electric-vehicle-compatible braking products, and manufacturing technologies that improve consistency and cost efficiency. Companies developing brake pad formulations that combine braking performance, durability, low noise, reduced dust, and improved environmental characteristics can address changing requirements from vehicle manufacturers and consumers.
The replacement market offers additional opportunities because brake pads require periodic replacement across a large installed vehicle base. Investments in regional distribution networks, e-commerce aftermarket channels, product authentication, workshop partnerships, and application-specific product portfolios can strengthen market access.
Related Reports-
Automotive Brake Adjusters Market
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean| German| Japanese| French| Chinese| Italian| Spanish
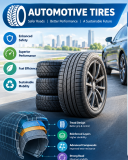
Automotive Tires with specialized tread designs provide improved grip and handling. Tread patterns are developed according to application requirements, including wet-road performance, dry-road traction, snow conditions, and off-road driving.
The Automotive Tires Market was valued at US$ 138.15 billion in 2023 and is projected to reach US$ 216.86 billion by 2031, registering a CAGR of 5.8% during 2022–2031. The market is expanding as vehicle production, replacement demand, road transportation, urban mobility, and advancements in tire technologies continue to support consumption across passenger cars, commercial vehicles, and other automotive applications. Manufacturers are increasingly focusing on durability, fuel efficiency, safety, rolling resistance, connected tire technologies, and sustainable materials.
What is driving the market?
Vehicle production and the expanding global vehicle parc are major drivers of the automotive tires market. Rising demand for passenger vehicles, commercial fleets, logistics transportation, and personal mobility increases both original-equipment and replacement-tire requirements. Tire replacement cycles, road usage, vehicle mileage, and maintenance requirements provide recurring demand across developed and emerging automotive markets.
Technology development is also changing tire specifications. Manufacturers are investing in low-rolling-resistance tires, improved tread compounds, lightweight designs, enhanced wet and dry grip, and tires compatible with electric vehicles. EV adoption is creating demand for tires capable of handling higher vehicle weight, instant torque, noise requirements, and efficiency considerations. At the same time, fluctuations in natural rubber, synthetic rubber, chemicals, steel, and energy costs remain important challenges for manufacturers.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPTE100001002
Which region leads?
Asia Pacific represents a major regional market for automotive tires, supported by vehicle manufacturing capacity, large automotive production bases, expanding road transportation, and increasing vehicle ownership. China, India, Japan, and other regional automotive manufacturing economies provide substantial demand for both original-equipment tires and replacement products. The region also benefits from the expansion of commercial transportation and logistics networks.
Europe and North America remain significant markets, supported by established automotive industries, large vehicle fleets, replacement demand, stringent vehicle and tire performance requirements, and increasing adoption of advanced and sustainable tire technologies. Regional demand is also being influenced by electric vehicle penetration, premium vehicle production, and regulatory requirements related to vehicle efficiency, safety, and environmental performance.
Which segment leads?
By Material Type
By Vehicle Type
By Body Structure
Which companies are prominent?
These companies participate across automotive manufacturing, engineering, lightweight components, metal products, automation, vehicle systems, and related technologies that contribute to the broader automotive tire and vehicle ecosystem. Competitive differentiation increasingly depends on manufacturing efficiency, lightweight materials, advanced engineering, automation, supply-chain integration, product innovation, and the ability to meet evolving vehicle performance and sustainability requirements. The listed companies represent the competitive landscape identified for the market and are not presented as a revenue-ranked market-share table.
What is changing in 2026?
The automotive tires industry is increasingly moving toward products designed for changing vehicle architectures, particularly electric and connected vehicles. Tire development is focusing on lower rolling resistance, improved durability, reduced road noise, enhanced load-bearing capacity, and optimized performance for electric powertrains. Tire manufacturers and automotive suppliers are also exploring sensors, digital monitoring, predictive maintenance, and connected tire systems that can provide information on pressure, temperature, wear, and operating conditions.
Sustainability is becoming another important area of development. Manufacturers are examining recycled and renewable materials, more efficient production processes, longer-lasting compounds, improved tire recovery, and technologies that can reduce resource consumption throughout the tire lifecycle. These developments are encouraging greater collaboration between tire manufacturers, automotive OEMs, material suppliers, recyclers, and technology providers.
What are the major investment opportunities?
Major opportunities exist in advanced tire materials, electric-vehicle-compatible tires, low-rolling-resistance technologies, smart tire systems, lightweight manufacturing, and sustainable tire production. Investments in materials that improve mileage, energy efficiency, wet grip, durability, and environmental performance can support product differentiation as vehicle requirements evolve.
Digital technologies provide additional opportunities through tire sensors, fleet monitoring, predictive maintenance, and connected mobility platforms. Commercial fleets in particular can benefit from technologies that monitor tire conditions and help reduce downtime, improve maintenance planning, and optimize operating costs.
Related Reports-
Automatic Tire Inflation System Market
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Also Available in : Korean| German| Japanese| French| Chinese| Italian| Spanish
Armored Vehicles Automatic Fire Extinguishing Systems typically combine fire detection sensors, control units, extinguishing agents, and strategically positioned discharge nozzles. The integrated configuration enables rapid response when a fire is detected.
The global Armored Vehicles Automatic Fire Extinguishing Systems Market was valued at US$ 106.11 million in 2025 and is projected to reach US$ 140.4 million by 2034, registering a CAGR of 3.16% during 2026–2034. The market is expanding as defense organizations and armored vehicle manufacturers prioritize crew protection, vehicle survivability, and rapid suppression of fires caused by ammunition, fuel, hydraulic systems, electrical components, and combat-related damage. Increasing modernization of armored fleets and integration of advanced fire detection and suppression technologies are supporting market development.
What is driving the market?
The growing emphasis on armored vehicle survivability and crew safety is a key factor driving demand for automatic fire extinguishing systems. Modern military vehicles operate in environments where fires can result from ballistic penetration, engine failures, fuel leakage, electrical faults, or thermal damage. Automatic systems can detect abnormal temperature or fire conditions and initiate suppression rapidly, reducing the potential for fire escalation and improving response time compared with manual intervention.
Defense modernization programs are also contributing to demand. Governments are investing in the upgrading and replacement of armored personnel carriers, infantry fighting vehicles, main battle tanks, and other protected platforms. These modernization programs increasingly incorporate integrated safety systems, including automatic fire detection and suppression technologies, as part of broader vehicle survivability packages.
Technological development is further influencing the market. Manufacturers are focusing on faster detection, improved sensing technologies, compact suppression equipment, reliable control units, and integration with vehicle electronics. However, high development and integration costs, stringent military qualification requirements, and the need to operate reliably under extreme vibration, temperature, and battlefield conditions remain important challenges.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPRE00020701
Which region leads?
North America represents a significant market for armored vehicles automatic fire extinguishing systems, supported by defense modernization programs, extensive armored vehicle fleets, and continued investment in vehicle protection and survivability. The United States remains an important source of demand due to procurement and upgrade programs covering armored combat vehicles and related safety technologies.
Europe is another important market, supported by defense spending, armored vehicle modernization, and increasing emphasis on battlefield survivability. Countries are upgrading existing platforms while developing next-generation armored vehicles, creating opportunities for integrated fire detection and suppression solutions.
Asia Pacific is expected to provide significant growth opportunities as countries expand and modernize their armored vehicle fleets. Rising defense investments, regional security requirements, indigenous defense manufacturing, and upgrades to military platforms are supporting demand for vehicle protection technologies. Countries with large armored vehicle inventories are also investing in modernization solutions that improve survivability without requiring complete fleet replacement.
Which segment leads?
By Platform
By System
Which companies are prominent?
The report identifies the following companies as prominent participants in the Armored Vehicles Automatic Fire Extinguishing Systems Market:
These companies participate across fire detection, suppression technologies, control systems, defense platforms, and specialized vehicle protection solutions. Competitive differentiation increasingly depends on detection speed, system reliability, integration capabilities, compliance with military standards, compact system design, and the ability to withstand demanding operational environments. The listed companies represent the competitive landscape and are not presented as a revenue-ranked market-share table.
What is changing in 2026?
The market is increasingly moving toward integrated and automated protection systems capable of detecting and responding to fire events with minimal human intervention. Armored vehicle manufacturers and defense organizations are placing greater emphasis on survivability technologies that can operate effectively during high-intensity missions and under severe environmental and mechanical conditions.
Modern systems are increasingly designed to integrate detection sensors, control units, suppression equipment, and vehicle electronics. This integration can support faster response and improved monitoring while enabling compatibility with increasingly sophisticated armored vehicle architectures.
Vehicle modernization is also creating opportunities for retrofit solutions. Defense forces can upgrade existing armored platforms with modern detection and suppression equipment rather than replacing entire vehicle fleets. This approach can support the extension of platform service life while improving safety and survivability capabilities.
What are the major investment opportunities?
Investment opportunities are emerging across advanced fire detection sensors, automatic suppression systems, electronic control units, and integrated vehicle safety technologies. Companies developing compact, lightweight, high-reliability systems can address the requirements of modern armored vehicles where available space, weight, and power consumption are important considerations.
Retrofit and modernization programs represent another opportunity. Large installed fleets of armored vehicles may require upgrades to meet evolving survivability and safety requirements. Suppliers capable of integrating new automatic fire extinguishing systems into legacy vehicle architectures can benefit from modernization spending.
Further opportunities exist in advanced sensing, digital monitoring, predictive maintenance, and connected vehicle safety systems. Technologies that provide real-time system status, fault identification, and maintenance information may improve operational readiness and lifecycle management.
Related Reports-
Armored Vehicle Market
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Bakery Processing Equipment includes mixers that combine flour, water, yeast, fats, and other ingredients to achieve consistent dough quality.
The global Bakery Processing Equipment Market is expected to register a CAGR of 5.58% during 2026–2034, with the market size expanding from US$ 13.55 billion in 2025 to US$ 22.08 billion by 2034. The market is expanding as commercial bakeries, food manufacturers, industrial baking facilities, and foodservice operators invest in automated equipment to improve production efficiency, consistency, hygiene, and throughput. Growth is supported by rising demand for baked foods, automation across bakery production lines, expansion of industrial bakeries, and the need to reduce labor-intensive processing activities.
What is driving the market?
Automation, increasing bakery production volumes, and demand for consistent product quality are major factors driving the bakery processing equipment market. Bakeries are adopting automated mixing, forming, depositing, proofing, baking, cooling, slicing, and packaging systems to improve productivity while reducing manual intervention. Equipment manufacturers are increasingly integrating automation and digital controls to support precise processing parameters, production monitoring, and operational efficiency.
The expansion of packaged bakery products is also contributing to equipment demand. Bread, rolls, cakes, pastries, cookies, biscuits, and other baked products require specialized processing technologies to maintain consistent texture, shape, weight, and quality. Industrial and large-scale bakeries are therefore investing in integrated processing lines capable of handling higher production volumes while maintaining standardized output.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPMC00002654
Which region leads?
Europe remains an important market for bakery processing equipment, supported by its established bakery industry, strong presence of equipment manufacturers, and high consumption of bread, pastries, biscuits, and other baked products. Demand is also influenced by investments in automation, energy-efficient machinery, and modern production facilities.
Asia Pacific is experiencing increasing demand as urbanization, changing consumer lifestyles, expanding foodservice sectors, and rising consumption of packaged bakery products support the development of commercial and industrial bakeries. China, India, Japan, and other regional markets are creating opportunities for equipment suppliers as bakery manufacturers modernize production facilities and increase automation.
North America is supported by established commercial baking operations and continuing investments in automated production technologies. Bakeries are focusing on equipment upgrades that can improve throughput, product consistency, labor efficiency, and operational flexibility.
Which segment leads?
By Product Type
By Application
Which companies are prominent?
The competitive landscape includes equipment manufacturers offering technologies across mixing, forming, baking, processing, handling, and automated bakery production lines. Prominent companies identified in the market include:
These companies compete through equipment performance, automation capabilities, production capacity, customization, after-sales services, energy efficiency, and integration with broader food-processing systems. Manufacturers are also focusing on solutions that allow bakeries to improve production flexibility and accommodate changing product specifications.
What is changing in 2026?
In 2026, bakery processing is increasingly moving toward automated and digitally monitored production environments. Manufacturers are adopting equipment equipped with advanced controls, sensors, automated adjustment capabilities, and production-monitoring systems. These technologies can help operators maintain consistent processing conditions and identify operational issues more efficiently.
Energy efficiency is another important consideration. Industrial baking requires significant energy for heating and processing, encouraging manufacturers to develop ovens and associated equipment designed to improve thermal efficiency. Bakery operators are also evaluating machinery based on maintenance requirements, production uptime, equipment integration, and total operating costs.
Flexible production is becoming increasingly relevant as bakeries expand their product portfolios. Equipment capable of handling different dough types, shapes, sizes, recipes, and production volumes can help manufacturers respond to changing consumer demand without requiring completely separate production systems.
Related Reports-
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
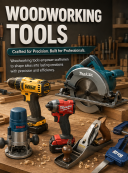
Woodworking Tools include saws, drills, chisels, planes, sanders, routers, and other equipment designed for different woodworking applications. Each tool serves a specific purpose and contributes to efficient material handling.
The global Woodworking Tools Market was valued at US$ 24.77 billion in 2025 and is projected to reach US$ 35.16 billion by 2034, registering a CAGR of 3.97% during 2026–2034. The market is expanding as professional woodworkers, furniture manufacturers, construction companies, contractors, and DIY users increase investment in tools that improve cutting precision, productivity, finishing quality, and operational efficiency. Growth is supported by furniture production, residential and commercial construction, renovation activity, woodworking automation, and demand for durable and ergonomically designed tools.
What is driving the market?
Growth in furniture manufacturing, construction, remodeling, and interior applications is a major driver of the woodworking tools market. Manufacturers and professional users increasingly require tools that deliver accurate cutting, drilling, shaping, sanding, routing, and finishing while reducing production time and material waste. Rising demand for customized furniture and specialized wood products is also encouraging workshops to expand their range of professional-grade equipment.
The market is also shifting toward cordless and power-assisted tools. Battery-powered saws, drills, sanders, routers, and other equipment provide greater mobility and reduce dependence on fixed electrical connections. Improvements in battery technology, brushless motors, electronic controls, and tool ergonomics are supporting adoption across professional and DIY applications. However, high costs for advanced equipment, maintenance requirements, and competition from lower-cost products remain important market constraints.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPRE00027297
Which region leads?
North America represents a significant market for woodworking tools, supported by established furniture manufacturing, residential construction, renovation, professional contracting, and a large DIY user base. The region benefits from the presence of established tool manufacturers and distributors, as well as strong demand for cordless and high-performance power tools.
Europe also holds an important position, supported by its furniture manufacturing industry, precision woodworking capabilities, construction activity, and established woodworking equipment ecosystem. Germany and other European manufacturing centers contribute to demand for precision machinery and professional woodworking tools.
Asia Pacific is an important growth market as furniture production, construction, urbanization, and manufacturing activity continue to expand. China, India, Japan, and other regional economies provide opportunities for tool manufacturers through growing industrial woodworking and expanding residential and commercial construction. Increasing workshop modernization and adoption of power tools are further supporting regional demand.
Which segment leads?
By Product Type
By Application
Which companies are prominent?
These companies compete across power tools, hand tools, cutting equipment, sanding and finishing solutions, precision woodworking equipment, and professional workshop systems. Competitive differentiation increasingly depends on cutting accuracy, motor performance, battery technology, durability, ergonomics, safety features, product reliability, and integration across broader tool platforms. The identified companies represent the competitive landscape rather than a revenue-ranked market-share table.
What are the major investment opportunities?
Major opportunities exist in cordless woodworking tools, advanced cutting systems, ergonomic equipment, battery platforms, precision tools, and workshop modernization. Continued development of high-performance batteries and brushless motor technology can support new generations of portable saws, drills, sanders, routers, and other woodworking equipment.
Furniture manufacturing and customized woodworking provide additional opportunities as producers seek flexible equipment capable of handling diverse designs and smaller production batches. Demand for precision tools is particularly relevant where manufacturers need consistent dimensions, smooth finishes, and reduced material losses.
Asia Pacific offers considerable expansion potential because of its manufacturing base, growing furniture production, construction activity, and workshop modernization. North America and Europe provide opportunities linked to renovation, professional contracting, replacement demand, and adoption of advanced cordless tools. Investors and manufacturers should focus on solutions that combine performance, durability, safety, energy efficiency, and competitive ownership costs.
Related Reports-
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Marine Mining involves the exploration and extraction of mineral resources from the seabed, ocean floor, and other underwater environments. It focuses on accessing valuable deposits that are difficult to obtain through conventional land-based mining.
The Marine Mining Market is projected to increase from US$ 945.6 million in 2025 to US$ 4,133.58 million by 2034, registering a CAGR of 17.81% during 2026–2034. The market is gaining momentum as demand for critical minerals, technological advancements in deep-sea exploration, and growing interest in alternative mineral resources encourage investment in offshore resource development. Marine mining involves the exploration and extraction of mineral deposits from seabeds, including polymetallic nodules, seafloor massive sulfides, and cobalt-rich crusts.
What is driving the market?
Rising demand for critical minerals used in batteries, renewable energy systems, electronics, and advanced industrial applications is a major driver of the marine mining market. Minerals such as nickel, cobalt, copper, and manganese are important inputs for various clean-energy and technology supply chains, increasing interest in alternative sources of mineral resources.
Growing pressure to diversify mineral supply chains is also encouraging governments, mining companies, technology providers, and research organizations to investigate seabed resources. Marine mining can potentially provide access to mineral deposits located in areas where terrestrial resources face increasing development, environmental, or supply constraints.
Technological progress is further supporting market development. Improvements in remotely operated vehicles, autonomous underwater systems, seabed mapping, drilling technologies, subsea equipment, mineral collection systems, and offshore processing capabilities are improving the ability to identify and assess deposits in challenging marine environments.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPRE00020884
Which region leads?
Asia Pacific represents a significant region for marine mining development due to its strong maritime industries, mineral demand, shipbuilding capabilities, offshore engineering expertise, and growing interest in securing critical mineral supplies. Countries across the region are investing in marine research, subsea technologies, and offshore resource exploration.
North America is also an important market, supported by technological capabilities, interest in critical-mineral supply-chain diversification, and research into deep-sea mineral resources. The region's established offshore engineering and marine technology ecosystem provides a foundation for developing advanced exploration and mining systems.
Europe continues to contribute through marine science, subsea engineering, environmental research, and regulatory development. European companies and research institutions are involved in technologies for seabed exploration, mineral assessment, underwater robotics, and responsible marine-resource development.
Which companies are prominent?
The Marine Mining Market includes companies and organizations developing exploration technologies, subsea equipment, mineral-resource projects, offshore engineering capabilities, and marine mining solutions. Prominent participants identified in the competitive landscape include:
These companies participate across different areas of the marine mining value chain, including seabed exploration, underwater robotics, mining equipment, offshore engineering, mineral-resource development, and project management. Competitive differentiation increasingly depends on subsea technology, operational reliability, environmental monitoring, mineral-processing capabilities, and the ability to develop commercially viable projects.
What is changing in 2026?
The marine mining industry is increasingly focused on moving from exploration and technology development toward more detailed resource assessment, environmental baseline studies, engineering validation, and regulatory preparedness. Companies are investing in advanced underwater vehicles, seabed mapping, sampling systems, remote monitoring, and automated equipment to improve knowledge of mineral deposits and operating conditions.
Environmental considerations are becoming an increasingly important component of marine mining development. Project developers are evaluating potential impacts on deep-sea ecosystems, sediment disturbance, biodiversity, water quality, and marine habitats. Environmental data collection and monitoring are therefore becoming closely integrated with exploration and engineering programs.
Regulatory development is also influencing investment decisions. Companies must consider applicable international and national requirements governing seabed exploration, mineral recovery, environmental management, and offshore operations. The evolving regulatory environment creates both challenges and opportunities for companies developing technologies designed to support transparent monitoring and responsible marine-resource management.
What are the major investment opportunities?
Major investment opportunities exist in deep-sea exploration technologies, remotely operated vehicles, autonomous underwater systems, seabed mapping, mineral sampling, subsea collection equipment, and environmental monitoring solutions. Technology providers capable of operating reliably at significant depths can benefit from increasing demand for specialized marine equipment.
Another opportunity lies in mineral-processing and offshore logistics. Efficient collection, transportation, separation, and processing technologies could become increasingly important as marine mining projects progress toward commercial development. Investments in supporting infrastructure and specialized vessels may also create opportunities across the broader marine mining value chain.
Related Reports-
Mining Waste Management Market
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Advancements in sensors, motors, connectivity, and automation are expanding the capabilities of residential solar shading systems. These technologies are making shading more responsive, convenient, and adaptable.
The Residential Solar Shading Systems Market was valued at US$ 16.89 Billion in 2025 and is projected to reach US$ 30.75 Billion by 2034, registering a CAGR of 6.89% during 2026–2034. The market is expanding as homeowners, residential developers, and architects adopt shade technologies to minimize heat gain, lower cooling energy consumption, and increase thermal comfort. Growth is supported by stringent building energy standards, home automation integration, retrofitting trends, and retrofits aimed at improving building aesthetics.
What is driving the market?
Rising residential energy expenses, growing awareness of building thermal efficiency, and the adoption of smart home technology are the primary market drivers. Homeowners are increasingly turning to interior and exterior shading systems to manage solar heat gain and natural lighting, directly reducing reliance on artificial HVAC cooling. Furthermore, environmental regulatory updates and energy efficiency incentives encourage residential integration. The shift extends past manual blinds and awnings toward automated and IoT-integrated dynamic systems. Suppliers are focusing on motorization, solar-powered controls, home automation compatibility, and high-performance technical fabrics. High upfront installation costs and complex retrofitting requirements for older structures remain notable restraints.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPRE00023233
Which region leads?
Europe leads the market, driven by strict green building directives, severe solar protection codes, and high adoption of automated exterior shading solutions across residential properties. North America holds a substantial share, propelled by retrofit investments, demand for smart motorized blinds, and growing adoption of outdoor living solutions. The Asia Pacific region represents a rapidly expanding market due to urbanization, expanding residential construction, and rising awareness of building energy management.
Which companies are prominent?
The report identifies Hunter Douglas, Lutron Electronics Co., Inc., Kawneer Company, Inc., WAREMA Renkhoff SE, Draper, Inc., EFCO Corporation, Skyco Shading Systems, Inc., Insolroll Window Shading Systems, Duco Ventilation and Sun Control, and Altex as prominent market participants.
These companies compete across custom architectural shading, automated motorized shades, interior/exterior window coverings, and energy-efficient textile systems. Strategic differentiation depends on smart home compatibility, fabric performance, architectural design, motorization technology, and distribution reach. The list reflects the competitive landscape rather than a revenue-ranked market-share table.
What is changing in 2026?
The market is shifting from standalone manual window coverings toward connected, climate-responsive residential shading. Shading specifications increasingly prioritize smart sensors (wind, sun, and temperature), voice assistant compatibility, automated schedule programming, and energy-harvesting motorized drives. Regulatory updates focusing on residential energy efficiency and net-zero building standards continue to drive baseline design requirements. Manufacturers are accelerating the deployment of smart-home compatible hubs, quiet motor units, high-performance recycled shading fabrics, and sleek architectural structural frames. Purchasing decisions are closely linked to ease of automation, thermal efficiency ratings, and long-term durability.
What are the major investment opportunities?
The strongest opportunities lie in smart motorization, automated climate-control integration, high-performance solar fabrics, and exterior shading retrofits. Investments in low-power wireless communication protocols, integrated solar-powered actuators, and automated sensor systems offer strong growth potential. Additional opportunities exist in sustainable and recycled textile development, eco-friendly powder coatings, and lightweight aluminum extrusions. Strategic partnerships between shading manufacturers, home automation platforms, and residential homebuilders can create long-term pipeline opportunities. Expanding residential construction across high-solar-irradiance regions presents prime geographical expansion targets.
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876
Modern utility boilers often operate at supercritical or ultra-supercritical pressures. Operating above the thermodynamic critical point eliminates a distinct phase change between liquid and steam, significantly boosting thermal efficiency and reducing overall carbon emissions.
The Utility Boiler Market was valued at US$ 47.85 billion in 2025 and is expected to reach US$ 80.59 billion by 2034, registering a CAGR of 5.96% during the forecast period 2026–2034. The market is expanding as power utilities, independent power producers (IPPs), and heavy industrial users modernize generation infrastructure to balance rising global electricity demand with stringent emission constraints. Growth is driven by the expansion of ultra-supercritical power capacity, retrofits aimed at improving thermal efficiency, flexible generation requirements to complement renewable integration, and strategic investments in high-capacity boiler systems.
What is driving the market?
Rising base-load power requirements, industrial electrification, and the transition toward lower-emission steam generation technologies serve as the core drivers for the global utility boiler market. Energy providers are increasingly replacing legacy subcritical units with supercritical and ultra-supercritical boilers designed to reduce fuel consumption and decrease carbon intensity per megawatt-hour generated.
The transition requires utility boilers to handle higher operational pressures and temperatures while accommodating fluctuating loads caused by variable renewable energy sources. Boiler manufacturers are investing in advanced creep-resistant alloys, low-NOx combustion systems, multi-fuel capabilities, and digital monitoring solutions for predictive maintenance. Regulatory pressure regarding air pollutant emissions, combined with the high cost of unplanned outages, continues to drive investment toward boiler upgrades, pressure part replacements, and comprehensive life-extension retrofits.
Get a PDF Sample- https://www.theinsightpartners.com/sample/TIPRE00027572
Which region leads?
Asia Pacific leads the utility boiler market, accounting for an estimated 38%–42% share in 2025, and remains the fastest-growing regional segment with a projected CAGR of 6.2%–6.8%. Growth is driven by rapid urbanization, massive industrial production, expanding electrification efforts, and major grid infrastructure expansion programs across the region. China and India represent key demand hubs due to ongoing additions of high-capacity supercritical power plants and modernization initiatives for existing thermal fleets.
North America holds an estimated 24%–28% share, supported by boiler control retrofits, fuel-switching projects (such as coal-to-gas conversions), and demand for high-efficiency industrial utility steam systems. Europe accounts for approximately 20%–24%, where the market focuses primarily on biomass co-firing, district heating utility systems, emissions compliance upgrades, and plant flexibility enhancements.
Which companies are prominent?
The report identifies Bharat Heavy Electricals Limited (BHEL), Thermax Limited, Babcock & Wilcox Enterprises, Inc., IHI Corporation, Mitsubishi Power, Ltd., General Electric Company, Larsen & Toubro Limited, Doosan Enerbility Co., Ltd., Siemens Energy AG, and John Wood Group PLC as prominent market participants.
These companies compete across supercritical pressure components, heavy fabrication, utility engineering, environmental control systems, and aftermarket lifecycle management. Strategic differentiation in the sector depends on metallurgy expertise, modular boiler engineering, flexible load capabilities, emissions-reduction technologies, and long-term service and maintenance agreements for installed fleets.
What is changing in 2026?
The market in 2026 is shifting focus from raw capacity addition toward grid-flexibility retrofits and digitalized thermal assets. Utility operators are configuring steam boilers for rapid ramp-up rates and lower minimum turndown loads to balance intermittent solar and wind input without causing thermal stress or equipment fatigue.
Strict regional emissions caps implemented across major industrial economies in 2026 are compelling operators to integrate advanced SCR (Selective Catalytic Reduction) systems, FGD (Flue Gas Desulfurization), and digital combustion optimization platforms. Procurement decisions are increasingly evaluated on total cost of ownership, operational flexibility, heat rate performance, and availability of digital twin monitoring packages.
What are the major investment opportunities?
The most lucrative investment opportunities exist in ultra-supercritical upgrades, flexible operation engineering, aftermarket service programs, and co-firing retrofits. Upgrading aging subcritical infrastructure to handle alternate fuels or higher operating parameters allows plant operators to extend plant lifetimes while reducing carbon footprints.
Additional opportunities lie in automated boiler control architectures, digital performance monitoring, pressure part replacement, and secondary heat recovery systems. The Asia Pacific and Southeast Asian energy markets present attractive capital expansion pathways due to ongoing utility scale-up, while North America and Europe offer stable opportunities in lifecycle extension, service contracts, and plant decarbonization technologies.
Related Reports-
About The Insight Partners
The Insight Partners is a leading market research and consulting firm delivering actionable insights through in-depth industry analysis and strategic intelligence. The firm supports clients across various industries in making informed business decisions by providing comprehensive market forecasts, competitive assessments, and growth opportunities.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Contact Person: Ankit Mathur
E-mail: sales@theinsightpartners.com
Phone: +1-646-491-9876