


The global industrial landscape is placing a profound emphasis on occupational safety, environmental sustainability, and operational efficiency. Central to this evolution is the deployment of industrial dust collectors essential systems engineered to filter out harmful particulate matter, gases, and airborne contaminants generated during manufacturing processes. According to a comprehensive research report by The Insight Partners, the Industrial Dust Collector Market size is expected to reach US$ 16.18 Billion by 2034 from US$ 10.2 Billion in 2025. The market is estimated to record a CAGR of 5.26% from 2026 to 2034.
Key Market Drivers and Trends
The expansion of the industrial dust collector market is fueled by a combination of strict regulatory frameworks and a growing awareness of health hazards in the workplace. Regulatory bodies globally have established rigorous permissible exposure limits (PELs) to guard against long-term respiratory ailments like silicosis, which are common in mining, construction, and manufacturing environments.
Beyond protecting human health, industrial dust collectors safeguard heavy machinery.Uncontrolled particulate accumulation can settle onto moving machine elements, accelerating equipment degradation, increasing mechanical failure rates, and driving up routine maintenance costs.Furthermore, managing combustible dust is paramount across sectors like woodworking, chemical processing, and food production, where excessive atmospheric dust significantly elevates the risks of catastrophic workplace explosions.
Technological evolution is also altering the market landscape. Modern manufacturing plants are shifting away from traditional systems that operate uniformly at maximum capacity, which strains electrical grids and increases facility costs. Instead, current design paradigms focus heavily on energy optimization, integrating advanced pulse-jet cleaning systems with automated pulse intervals and intelligent variable speed drives. These intelligent systems alter power usage dynamically depending on real-time operational loads, promoting eco-friendly, energy-efficient manufacturing.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00009160
Industry Key Players
The global industrial dust collector marketplace features a mixture of established multinational engineering corporations and specialized filtration technology providers. These players are focused on continuous product development, strategic partnerships, and regional expansions to meet evolving clean-air standards.
Key players operating in the industrial dust collector market include:
3M
Aerotech Inc.
Alstom SA, Ltd
American Air Filter Company, Inc.
Atlas Copco
Beltran Technologies, Inc
Camfil APC
CECO Environmental
Donaldson Company, Inc
Nederman Holding AB
These organizations are progressively engineering modular, highly adaptable filtration configurations. These systems help diverse industrial end-users minimize their ecological footprint while maintaining compliance with local workplace regulations.
Market Segmentation and Insights
The market is analyzed across various parameters, including technology types, product categories, and end-user industries. By technology, the market includes:
Baghouse Dust Collectors: Widely preferred for heavy-duty industrial processing because of their ability to handle immense volumes of gas and highly diverse, coarse particulate streams.
Cartridge Collectors: Highly valued in facilities with limited space where high-efficiency filtration of fine, sub-micron airborne dust is necessary.
Cyclone Dust Collectors: Utilizing centrifugal forces to isolate larger, abrasive particles before they can reach secondary filters, lowering overall equipment wear.
Electrostatic Precipitators (ESPs): Utilizing electrical charging fields to trap ultra-fine particulates from exhaust gases with very little resistance to industrial airflow.
From an end-user standpoint, key sectors such as cement production, pharmaceutical manufacturing, metallurgy, chemicals, and food processing remain the primary consumers. The continuous mechanization and automation within these spaces demand consistent, high-capacity air filtration to sustain peak manufacturing uptime.
Future Outlook
Looking ahead, the future of the industrial dust collector market will be defined by the integration of Industry 4.0 technologies and the push toward net-zero industrial emissions. The deployment of Internet of Things (IoT) sensors within dust collection systems is moving the market from reactive maintenance to predictive servicing. Real-time tracking of filter pressure drops, airflow velocities, and particulate emissions will allow operations teams to address system inefficiencies before component failures occur.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global infrastructure landscape is undergoing a massive transformation, driven by rapid urbanization, aging municipal systems, and a heightened public focus on hygiene and sanitation. At the heart of this transformation is the maintenance of vital underground utilities. The Sewer and Drain Cleaning Services Market size is expected to reach US$ 8,415.25 million by 2031 from US$ 5,565.87 million in 2024. The market is estimated to register a CAGR of 6.0% during 2025–2031. This steady trajectory reflects the indispensable nature of specialized plumbing, maintenance, and wastewater management infrastructure in both residential and industrial sectors worldwide.
Market Drivers and Changing Infrastructure Demands
Several macro-economic and technical factors are propelling the sewer and drain cleaning services sector forward. In many developed regions, municipal pipeline networks have been operational for decades, making them highly susceptible to structural deterioration, root intrusion, and severe blockages. Concurrently, expanding urban centers in developing economies are putting an unprecedented load on existing wastewater frameworks.
Environmental regulations have also become considerably stricter. Regulatory authorities are increasingly penalizing commercial entities and municipalities for sewage overflows or untreated wastewater leaks, prompting a shift from reactive emergency repairs to proactive, scheduled maintenance protocols. Furthermore, extreme weather events caused by shifting global climates have resulted in frequent flooding, placing immense pressure on storm drains and demanding immediate, high-capacity cleaning interventions.
Technological Advancements Reshaping the Market
The industry is moving away from purely mechanical, invasive rod-and-cable methods toward sophisticated, technology-driven diagnostic and cleaning procedures. High-definition closed-circuit television (CCTV) camera inspections have become standard practice, allowing technicians to locate structural defects or blockages with pin-point accuracy without digging.
For clearance, hydro-jetting technology which utilizes ultra-high-pressure water streams to blast away grease, scale, and debris is heavily favored for its efficiency and eco-friendliness, as it eliminates the need for harsh chemical cleaners. Additionally, trenchless pipe rehabilitation techniques like Cured-in-Place Pipe (CIPP) lining are gaining popularity, enabling service providers to repair internal pipe structures from within existing access points, saving clients both time and significant excavation costs.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00040907
Key Industry Players
The competitive arena of the sewer and drain cleaning services market features a mix of massive, franchised commercial networks and highly specialized regional industrial contractors.
Key players operating in this space include:
Clean-Co Systems
Len The Plumber
Rooter Hero Plumbing
Benjamin Franklin Franchising SPE LLC.
Roto-Rooter Group Inc
Modern Plumbing Industries, Inc.
Mr. Rooter
Bob Oates
Haller Enterprises
Neptune Plumbing
Augusta Industrial Services
Frank’s Repair Plumbing, Inc.
These organizations are actively sustaining their market dominance by investing in advanced fleet vehicles, expanding their geographic service footprints through franchise networks, and implementing digital scheduling and dispatch platforms to enhance customer experience.
Future Outlook
Looking ahead, the sewer and drain cleaning services market is poised to become smarter and more integrated. The future of the industry lies in the adoption of Internet of Things (IoT) sensors within municipal and commercial plumbing networks, allowing for real-time monitoring of flow rates and sediment accumulation. This shift will enable service providers to transition completely into predictive maintenance models, clearing structural vulnerabilities before a physical backup even occurs. Additionally, as water scarcity escalates globally, technologies that recycle hydro-jetting water directly inside service trucks are expected to gain widespread adoption. Backed by expanding smart city initiatives and an unyielding global demand for sanitary living conditions, the market will remain a resilient and highly lucrative sector of the broader utility infrastructure industry through 2031 and beyond.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
Driven by early technology adoption and a mature aviation ecosystem, the North America airline retailing market is experiencing substantial modernization. The United States, in particular, acts as a primary hub for this transition, as major carriers aggressively integrate IATA’s New Distribution Capability (NDC) standards to bypass legacy distribution bottlenecks. North American airlines are heavily prioritizing hyper-personalization, utilizing cloud infrastructure and artificial intelligence to offer tailored ancillary options such as customized baggage pricing, premium lounge access, and co-branded credit card loyalty rewards directly through mobile applications. Furthermore, the presence of major travel technology providers in the region guarantees continuous software innovation, ensuring that North American passenger experiences remain highly frictionless and retail-centric throughout the travel journey.
The commercial aviation landscape is undergoing a massive paradigm shift. Driven by a transition from traditional ticketing to dynamic, customer-centric commerce, the global aviation industry has embraced advanced digital strategies. Today, airlines no longer view themselves as mere transport providers; they operate as modern digital retailers.
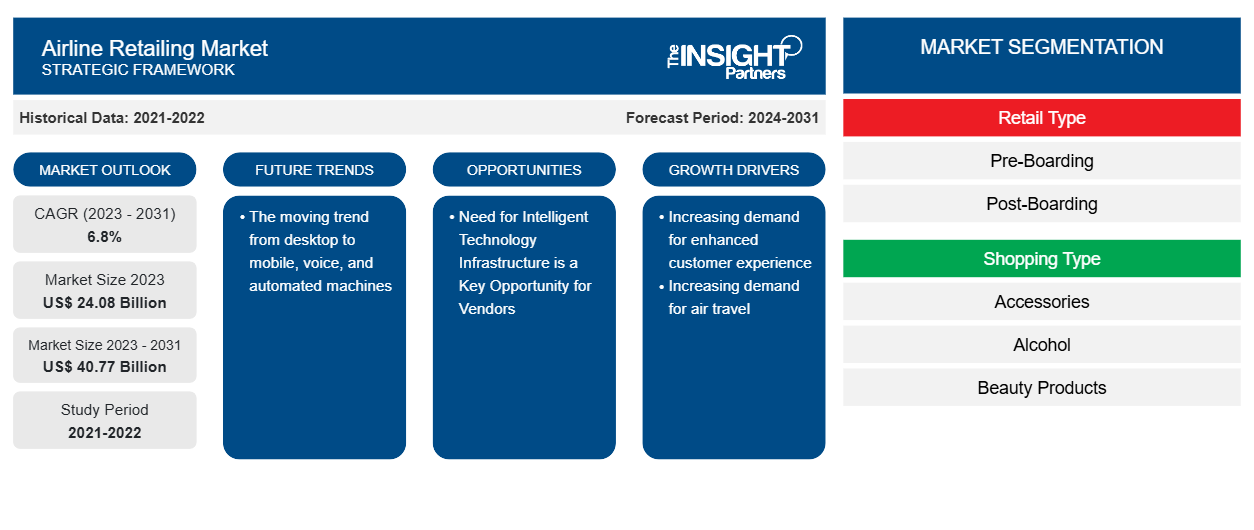
According to a comprehensive study by The Insight Partners, the global Airline Retailing Market size is projected to reach US$ 40.77 billion by 2031 from US$ 24.08 billion in 2023. The market is expected to register a CAGR of 6.8% during the forecast period of 2023–2031. This steady growth highlights the rapid adoption of digital storefronts, personalized ancillary services, and artificial intelligence-driven dynamic pricing models designed to elevate the traveler experience.
Bearings are fundamental components in modern engineering, serving as the invisible backbone for virtually everything that rotates, rolls, or moves. From massive industrial wind turbines to the micro-motors found in medical devices, these precision-engineered components are critical for reducing friction and handling heavy mechanical loads. According to a comprehensive research report by The Insight Partners, the global bearing industry is currently experiencing a transformative growth phase, driven by rapid industrialization, automation, and the global shift toward cleaner energy systems.
Market Valuation and Growth Trajectory
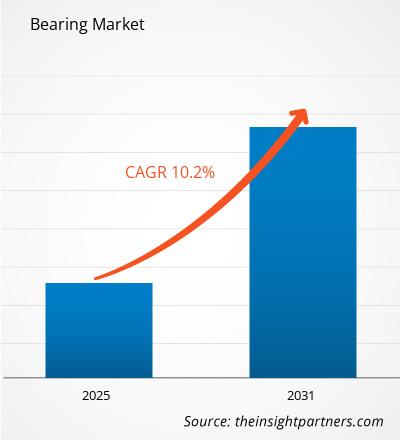
The Bearing Market size is projected to reach US$ 210.864 billion by 2031 from US$ 127.912 billion in 2024. The market is expected to register a CAGR of 7.51% during 2025–2031. This robust growth trajectory highlights an escalating demand across diverse sectors, particularly automotive, aerospace, heavy machinery, and robotics.
As developing economies expand their manufacturing infrastructure and developed nations modernize their industrial plants with IoT-enabled technologies, the reliance on high-quality, long-lasting bearings has never been higher. The steady Compound Annual Growth Rate (CAGR) reflects a market that is not just expanding in volume, but also shifting toward higher-value, specialized bearing solutions.
Primary Growth Drivers
Several macro-economic and technological trends are fueling this market expansion:
The Electric Vehicle (EV) Revolution: The automotive industry is undergoing its most significant shift in a century. EVs require specialized bearings that can operate smoothly at much higher rotational speeds (RPMs) while minimizing noise, vibration, and harshness (NVH). Furthermore, these bearings must offer low friction to maximize battery range and prevent electrical arcing from damaging internal components.
Industrial Automation and Robotics: The rise of Industry 4.0 has led to widespread deployment of automated manufacturing lines and robotic arms. These systems demand high-precision miniature and slewing bearings capable of precise, repetitive movements over millions of cycles without failure.
Renewable Energy Infrastructure: The global push for green energy has led to massive investments in wind power. Wind turbines rely heavily on large-diameter main shaft and gearbox bearings that can withstand extreme, unpredictable aerodynamic loads and harsh environmental conditions over a multi-decade lifespan.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPTE100000700
Key Market Players
The global bearing market is highly competitive, characterized by a mix of established legacy manufacturers who continually innovate to maintain their market share. The prominent companies leading the industry include:
SKF (Sweden) – A global leader recognized for its extensive range of rolling bearings, seals, and lubrication systems, heavily focusing on digital monitoring and sustainability.
Schaeffler Group (Germany) – Renowned for its INA and FAG brands, driving innovation in high-precision components for automotive engines, transmissions, and industrial applications.
The Timken Company (USA) – A specialist in tapered roller bearings, widely trusted for heavy-duty industrial machinery, rail, and aerospace applications.
NSK Ltd. (Japan) – One of the foremost suppliers of ball bearings and automotive components, known for exceptional reliability and motion control technologies.
NTN Corporation (Japan) – A major global supplier specializing in eco-friendly bearing designs and constant velocity joints for the automotive sector.
NACHI-FUJIKOSHI CORP. (Japan) – A versatile manufacturer integrating bearing production with cutting tools, hydraulics, and industrial robotics.
JTEKT CORPORATION (Japan) – Known for its Koyo bearing brand, providing advanced steering systems and high-performance bearings across global supply chains.
These industry giants are aggressively investing in Research and Development (R&D) to develop "smart bearings" equipped with integrated sensors. These sensors monitor temperature, vibration, and lubrication levels in real time, allowing operators to perform predictive maintenance before a catastrophic failure occurs.
Future Outlook
The future of the bearing market points toward a convergence of material science and digital technology. Over the coming years, expect to see accelerated adoption of ceramic and hybrid bearings which utilize silicon nitride ceramic balls inside steel rings due to their superior heat resistance, lower weight, and electrical insulation properties. Furthermore, sustainability will become a core focus; manufacturers are increasingly utilizing recycled steel and carbon-neutral production processes to meet strict corporate environmental goals. As industries across the globe continue to prioritize energy efficiency, the development of ultra-low-friction bearings will remain paramount, solidifying the bearing industry's role as a vital catalyst for global economic and technological progress.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The aerospace industry relies on structural components that ensure vehicle integrity, passenger comfort, and operational safety. Among these critical elements, aircraft engine mounts play a fundamental role. These specialized components connect the aircraft engine to the fuselage or wing pylons. Beyond providing mechanical support, engine mounts absorb severe engine vibrations, secure heavy propulsion systems, and minimize structural stress transferred to the airframe during flight maneuvers. Driven by a surge in commercial airline fleets, continuous military modernizations, and rapid breakthroughs in lightweight materials, this sector is poised for substantial financial expansion.
Market Size and Significant Projections
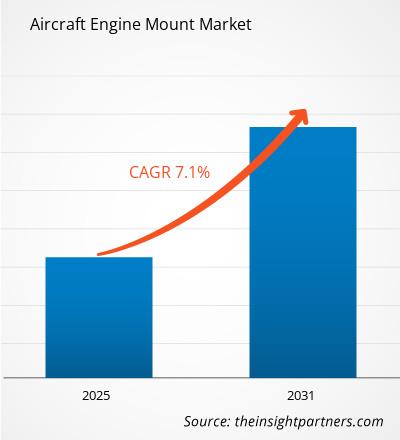
According to a comprehensive industry study, the global aircraft engine mount market is entering a phase of robust, continuous growth. The Aircraft Engine Mount Market size is expected to reach US$ 1,741.57 Million by 2034 from US$ 918.92 Million in 2025. This long-term expansion highlights a stable market trajectory, with the industry estimated to record a CAGR of 7.36% from 2026 to 2034.
This sustained growth is heavily supported by the increasing global demand for single-aisle commercial aircraft, alongside a massive push to replace aging fleets with fuel-efficient, next-generation variants. Because engine mounts must endure extreme thermal conditions and intense kinetic forces, they are subject to regular, stringent maintenance and replacement schedules. This routine maintenance establishes a highly profitable aftermarket segment that complements original equipment manufacturer (OEM) demands.
Market Growth Drivers and Technical Shifts
Modern aviation demands quieter, lighter, and more aerodynamically efficient aircraft. To fulfill these design requirements, engine manufacturers have introduced high-bypass and ultra-high-bypass turbofan engines. While these propulsion systems offer superior fuel economy, they feature larger fan diameters and significantly increased weight. Consequently, aircraft structures must adapt, leading to the development of advanced engine mounts capable of distributing immense thrust loads without altering the aircraft's center of gravity or exceeding strict weight budgets.
Material science acts as another primary catalyst driving market growth. Traditional engine mounts constructed from standard steel alloys are steadily being replaced by high-performance materials. Advanced titanium alloys, nickel-based superalloys, and carbon fiber composite integrations are increasingly favored by modern aerospace designers. These advanced materials provide exceptional strength-to-weight ratios and superior resistance to corrosion and thermal fatigue, directly expanding product lifecycles and lowering long-term maintenance overhead for global commercial operators.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00029696
Competitive Landscape and Key Industry Players
The global aircraft engine mount market is characterized by a mix of established tier-1 aerospace component manufacturers, specialized engineering firms, and comprehensive aviation technology companies. These organizations focus on collaborative design cycles with major airframe and engine OEMs, expanding their domestic production capabilities, and dedicating capital to advanced metallurgy and elastomeric dampening research.
Prominent market participants steering the technical development and distribution of aircraft engine mounts include:
Acorn Welding
Cadence Aerospace
Continental Aerospace Technologies
EPI Inc.
Honda Aircraft Company
Parker Hannifin Corporation
SAM Suzhou
The Wag Aero Group
VAN'S AIRCRAFT, INC.
Strategic partnerships, long-term procurement contracts with defensive bodies, and precision additive manufacturing (3D printing) represent the core methodologies utilized by these key entities to secure market share and meet evolving custom engineering specifications.
Future Outlook
Looking ahead, the aircraft engine mount market will transform in parallel with the foundational evolution of modern aviation design. Over the next decade, the industry will pivot toward supporting advanced aerial mobility, electric vertical takeoff and landing (eVTOL) aircraft, and hybrid-electric propulsion systems. These emerging electric configurations present entirely unique engineering challenges, demanding engine mounts optimized for high-frequency electrical isolation and minimal acoustic profiles rather than traditional high-thrust dampening. Furthermore, the increasing integration of smart sensors into component structures will enable real-time health monitoring and predictive maintenance. By allowing structural flaws to be diagnosed before component failure occurs, these advanced technologies will enhance international flight safety and cement the engine mount sector's role in the future of automated, highly efficient aerospace ecosystems.
Related Reports-
Aircraft Engine Forging Market
Aircraft Engine Compressor Market
Aircraft Engine Fuel Systems Market
Aircraft Engine Component Market
North America Aircraft Engine Forging Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global automotive landscape is undergoing a monumental paradigm shift, transitioning rapidly from traditional internal combustion engines (ICE) to electric and hybrid vehicles. At the heart of this transformation is the lithium-ion battery pack, a component that demands precise environmental conditions to operate safely, efficiently, and durably. Consequently, the reliance on advanced cooling and heating infrastructure within vehicles has intensified, turning battery thermal management into a cornerstone of modern automotive engineering.
The Automotive Battery Thermal Management System Market size is expected to reach US$ 10.53 billion by 2031. The market is anticipated to register a CAGR of 15.2% during 2025-2031. This robust growth trajectory underscores the escalating production of electric vehicles (EVs), breakthroughs in battery chemistry, and stringent regulatory mandates worldwide aimed at curbing vehicular emissions.
Batteries are highly sensitive to temperature fluctuations. Operational environments that are too hot accelerate degradation, reduce driving range, and in extreme scenarios trigger thermal runaway, a catastrophic chain reaction leading to fires. Conversely, extremely cold temperatures severely restrict a battery's ability to accept or deliver a charge, diminishing performance and slowing down fast-charging capabilities.
Automotive battery thermal management systems (BTMS) resolve these issues by utilizing technologies such as liquid cooling, air cooling, phase change materials (PCM), and thermoelectric modules. By maintaining the battery pack within its optimal temperature window (typically between 20°C and 40°C), these systems optimize energy efficiency, ensure passenger safety, and extend the overall lifespan of the vehicle's powertrain.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00006121
Several critical factors are propelling the expansion of the BTMS market. First, the consumer demand for driving range autonomy has pushed automakers to deploy larger battery capacities and higher voltage architectures (such as 800V systems). Higher voltage architectures enable ultra-fast charging, but they also generate massive amounts of heat during the charging cycle, necessitating highly sophisticated liquid-cooling circuits.
Furthermore, governments globally are introducing strict fuel economy standards and offering lucrative incentives for EV adoption. This regulatory tailwind is forcing original equipment manufacturers (OEMs) to invest heavily in next-generation thermal management architectures. Integration is another key trend; modern systems do not just cool the battery in isolation but manage the thermal needs of the electric motor, power electronics, and passenger cabin holistically to conserve every watt of energy.
The global marketplace is characterized by intense competition, featuring a mix of established automotive tier-1 suppliers and specialized technology providers investing aggressively in research and development. Key players shaping the competitive landscape include:
Calsonic Kansei Corporation
Continental AG
Dana Incorporated
Gentherm Incorporated
Hanon Systems
LG Chem Ltd.
MAHLE GmbH
Robert Bosch GmbH
SAMSUNG SDI CO., LTD.
Valeo
These industry leaders are focused on scaling production, forming strategic partnerships with OEMs, and pioneering lightweight, compact thermal components to reduce the overall weight of electric vehicles.
Future Outlook
The future of the Automotive Battery Thermal Management System market points toward a highly integrated and intelligent ecosystem. As solid-state batteries edge closer to commercialization, thermal requirements will evolve, demanding systems capable of managing unique pressure and high-temperature operating thresholds. Additionally, the integration of artificial intelligence and predictive software into vehicle energy management will allow future BTMS to anticipate thermal loads based on driving habits, GPS terrain data, and weather forecasts. This shift from reactive cooling to proactive, intelligent thermal orchestration will significantly enhance EV range and charging speeds, securing BTMS as an indispensable technology in the next generation of autonomous and electrified transportation.
Related Reports-
Electric Vehicle Battery Swapping Market
Battery Production Machine Market
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global aviation ecosystem relies heavily on the efficiency and reliability of its ground operations. Among these, line maintenance stands as the frontline defense against mechanical delays, technical disruptions, and safety compromises. Executed primarily on the tarmac during routine turnarounds or transit periods, line maintenance ensures that aircraft are strictly airworthy before every takeoff. As global passenger traffic rebounds sharply and airline fleets expand across the globe, the strategic importance of this sector has reached unprecedented heights.
Market Valuation and Growth Dynamics
According to the latest comprehensive intelligence by The Insight Partners, the financial trajectory of this industry points toward robust long-term expansion. The Aircraft Line Maintenance Market is projected to reach US$ 39.49 billion by 2034 from US$ 24.68 billion in 2025. This steady climb represents an anticipated Compound Annual Growth Rate (CAGR) of 5.36% during the forecast period from 2026 to 2034.
This sustained growth is driven by several macroeconomic factors. The influx of next-generation aircraft models, the establishment of fresh regional flight corridors, and increasingly stringent global aviation safety regulations are compelling operators to ramp up their routine maintenance schedules. Furthermore, as commercial airlines strive to maximize the operational utilization of their active fleets, minimizing ground time while ensuring flawless mechanical compliance has become a core commercial imperative.
Market Drivers
Line maintenance encompasses a variety of light, pre-flight, and overnight checks that do not require the aircraft to be removed to a dedicated hangar environment. Key services include daily or weekly checks, fluid top-ups, wheel and brake replacements, and minor structural repairs.
One of the prominent trends steering the market is the outsourcing model. Due to the immense capital expenditure required to establish and staff dedicated line stations at every destination airport, many airlines are opting to partner with specialized Third-Party Maintenance, Repair, and Overhaul (MRO) providers. This enables carriers to cut fixed overhead costs, leverage localized expertise, and maintain flexible operational networks across international hubs.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPTE100001325
Competitive Landscape and Key Players
The global landscape is highly competitive, characterized by a mix of specialized independent MRO facilities, joint ventures, and the technical divisions of major commercial airlines. These organizations are continually expanding their line station footprints to secure lucrative long-term servicing contracts with international airlines.
The prominent and influential market participants shaping the industry include:
British Airways
Delta TechOps
FL Technics
Hong Kong Aircraft Engineering Company Limited (HAECO)
Lufthansa Technik AG
SAMCO Aircraft Maintenance B.V.
SIA Engineering Company Ltd.
SR Technics Switzerland AG
Turkish Technic
United Airlines, Inc.
These key players are actively investing in technician training programs, geographic facility expansion, and advanced diagnostic tooling to maintain their market dominance and cater to the evolving needs of modern aircraft fleets.
Future Outlook
Looking ahead, the future of the aircraft line maintenance market will be fundamentally defined by automation, digital transformation, and the integration of predictive maintenance capabilities. The traditional "run-to-failure" or strictly reactive maintenance approaches are rapidly giving way to data-driven ecosystem networks. Modern aircraft equipped with advanced IoT sensors generate massive volumes of real-time telemetry data while in flight. Forward-thinking line maintenance providers are leveraging this data alongside AI-driven diagnostic platforms to predict mechanical faults before the plane even lands. This allows line crews to pre-stage parts, tools, and certified technicians directly at the arrival gate, virtually eliminating unexpected structural delays. Additionally, the adoption of augmented reality (AR) smart glasses for remote tech support and digital logbooks will streamline workflow efficiencies. Over the 2026–2034 forecast horizon, this digital shift will not only optimize operational turn times for airlines but also reshape the baseline capabilities required by MRO providers to remain competitive in a highly dynamic global airspace.
Related Reports-
Military Equipment Maintenance Repair and Overhauling Services Market
Aircraft Engine Forging Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global oilfield auxiliary rental equipment market is undergoing a significant transformation, driven by shifting dynamics in the oil and gas sector, technological advancements, and a growing emphasis on operational efficiency. As exploration and production (E&P) activities venture into more challenging environments, such as deepwater and unconventional shale plays, the demand for specialized support equipment has surged. Navigating this landscape requires robust infrastructure, which is why market players increasingly rely on equipment rental models to manage capital expenditure (CAPEX) while optimizing production capabilities.
Market Size and Growth Trajectory
The global Oilfield Auxiliary Rental Equipment Market size is projected to reach US$ 50.74 Billion by 2034 from US$ 34.03 Billion in 2025. The market is anticipated to register a CAGR of 4.4% during the forecast period 2026–2034.
This steady growth highlights a fundamental shift in how oilfield operators approach asset management. Instead of outright purchasing auxiliary machinery—such as specialized drilling tools, pressure control equipment, power generation units, and waste management systems—companies are turning to rental services. The rental model provides operators with the agility to scale operations up or down based on market volatility and regional project demands, mitigating the financial risks associated with underutilized or depreciating physical assets.
Market Drivers and Dynamics
Several macro-economic and industry-specific factors are fueling the expansion of the oilfield auxiliary rental equipment market. First, the recovery and stabilization of global crude prices have revitalized drilling activities across mature basins and new frontiers alike. However, despite increased budgets, operators remain cautious about capital allocation. By prioritizing operating expenditure (OPEX) through rental equipment over CAPEX, oil and gas companies maintain healthier balance sheets.
Furthermore, stringency in environmental regulations is playing a massive role. Auxiliary equipment related to waste management, spill containment, and emissions control must now meet strict compliance standards. Rental companies specialize in providing the latest, legally compliant technology, saving operators the hassle and cost of constantly upgrading their proprietary fleets. Technological innovation, including the integration of IoT-based monitoring and predictive maintenance in rental fleets, has also increased the reliability of these outsourced assets, reducing costly non-productive time (NPD) on site.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00021336
Key Players in the Global Landscape
The ecosystem of the oilfield auxiliary rental equipment market comprises a mix of leading exploration and production companies, integrated oilfield service giants, and specialized equipment providers. The prominent entities shaping the market include:
BP
CNPC (China National Petroleum Corporation)
Key Energy Services
Occidental Petroleum
Oil States International
Schlumberger (SLB)
Shell
Superior Energy Services
Total (TotalEnergies)
Weatherford
These major players are driving market evolution through strategic mergers and acquisitions, geographic expansions, and heavy investments in digitalizing their rental asset portfolios to offer more value-driven services to end-users.
Future Outlook
The future of the oilfield auxiliary rental equipment market looks promising, characterized by a dual focus on digital transformation and sustainable operations. Moving forward, the industry will likely see widespread adoption of "smart" rental equipment equipped with advanced sensors that feedback real-time data to operators, maximizing efficiency and safety during complex drilling operations. Additionally, as the global energy transition accelerates, rental companies that adapt their fleets to include low-carbon auxiliary equipment, solar-powered generators, and highly efficient eco-friendly machinery will capture a competitive edge. Despite the cyclical nature of the oil and gas sector, the intrinsic cost benefits and operational flexibility offered by auxiliary rentals guarantee that this market will remain an indispensable pillar of global upstream operations through 2034 and beyond.
Related Reports-
Oilfield Equipment Rental Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The global industrial landscape is experiencing a significant paradigm shift, with a heightened focus on thermal efficiency, process optimization, and sustainability. At the heart of this transition is the insulated storage vessels market, which plays a critical role in preserving the integrity of temperature-sensitive liquids, gases, and chemicals across diverse sectors. These highly engineered containment systems prevent heat transfer, ensuring that materials remain at precise thermal thresholds during processing, transit, and long-term storage. From food and beverage processing to oil and gas, pharmaceuticals, and chemical manufacturing, the demand for high-performance insulation technologies is escalating rapidly.
Market Valuation and Growth Trajectory
Reflecting this broad-based industrial demand, the market is poised for robust expansion over the next decade. The Insulated Storage Vessels Market size is expected to reach US$ 7.34 Billion by 2034 from US$ 4.90 Billion in 2025. The market is anticipated to register a CAGR of 4.59% during the forecast period 2026–2034.
This steady growth trajectory is primarily propelled by strict environmental and safety regulations mandating energy conservation. Industries are increasingly replacing outdated, uninsulated tanks with modern, double-walled, or vacuum-insulated solutions to minimize product boil-off, prevent emissions, and reduce energy consumption. Additionally, the rapid expansion of the global liquefied natural gas (LNG) network and the emerging hydrogen economy are acting as major catalysts, fueling the adoption of specialized cryogenic insulated vessels.
Key Drivers and Market Dynamics
Several macroeconomic and technological factors are shaping the expansion of the insulated storage vessels market. In the food and beverage industry, maintaining strict temperature controls is vital for hygiene, product quality, and extending shelf life. Breweries, dairy processing plants, and juice manufacturers heavily rely on stainless steel insulated vessels to manage fermentation and storage temperatures.
In the chemical and pharmaceutical industries, precise thermal stabilization prevents volatile substances from degrading or posing safety hazards. Furthermore, urbanization and industrialization in developing regions particularly across Asia-Pacific and Latin America are leading to substantial investments in wastewater treatment facilities and chemical processing plants. These infrastructure developments naturally drive the bulk procurement of durable, corrosion-resistant, and thermally insulated containment units.
Innovation in insulation materials is another pivotal factor. Manufacturers are shifting from traditional fiberglass or polyurethane foam toward advanced materials like vacuum insulation panels (VIPs) and multi-layer insulation (MLI). These innovations offer superior thermal resistance with thinner profiles, maximizing the internal storage capacity of the vessels while drastically reducing structural weight.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00021330
Prominent Industry Participants
The global marketplace features a mix of established multinational corporations and specialized engineering firms focusing on localized custom solutions. The key players steering innovation and market penetration include:
Comap S.r.l. – Renowned for high-quality industrial processing and thermal containment systems.
Della Toffola SpA – A major global provider of advanced storage and processing vessels, particularly for the beverage and winemaking industries.
Fletcher European – Specializes in heavy-duty, hygienic material handling and insulated storage containers for food logistics.
Indian Oil Corporation Ltd. – A dominant energy enterprise driving large-scale infrastructure deployment for petroleum and chemical insulated storage.
Kingspan Group – A global leader in high-performance insulation and building envelope solutions, contributing significantly to thermal containment technology.
Müller Group – Widely recognized for precision-crafted stainless steel handling and storage systems tailored for pharmaceuticals and fine chemicals.
Pneumatech MGS – Specialized in gas generation and industrial air equipment, providing robust pressurized containment systems.
Toro Equipment – A leading manufacturer of wastewater treatment equipment, offering specialized tanks for wastewater and sludge storage.
Wärtsilä – A global leader in innovative technologies and lifecycle solutions for the marine and energy markets, heavily involved in LNG storage and cryogenic vessel engineering.
Werner Sölken – Renowned for engineered tank systems and industrial components focusing on fluid storage and environmental safety.
Future Outlook
The future of the insulated storage vessels market remains highly optimistic, deeply intertwined with the global transition toward a low-carbon economy. As nations accelerate their investments in clean energy, the demand for highly sophisticated cryogenic insulated vessels will skyrocket to support the storage and distribution of liquid hydrogen and ammonia. Furthermore, the integration of IoT-enabled smart sensors into storage vessels will redefine inventory and thermal management. These digital solutions will allow plant operators to monitor real-time temperature fluctuations, structural integrity, and pressure levels remotely, ensuring maximum safety and operational efficiency. Moving forward, continuous breakthroughs in sustainable insulation materials and automated manufacturing techniques will unlock new growth horizons, solidifying insulated storage vessels as indispensable assets in the modern industrial infrastructure.
Related Reports-
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876
The automotive industry is undergoing a profound transformation driven by rapid technological innovations, stricter safety regulations, and shifting consumer preferences. At the forefront of this evolution is the automotive lighting sector, particularly rear lighting systems. Beyond their foundational role in ensuring vehicle safety and visibility, rear lights have morphed into vital design elements that define a vehicle’s aesthetic identity and enhance communication with other road users.
According to a comprehensive study by The Insight Partners, the Automotive Rear Lights Market size is expected to reach US$ 28.35 Billion by 2034 from US$ 14.69 Billion in 2025. The market is anticipated to register a CAGR of 7.58% during the forecast period 2026–2034. This robust growth reflects the increasing integration of advanced lighting technologies and the global surge in automobile production.
Driving Factors and Technological Evolution
The steady growth of the automotive rear lights market is fueled by multiple compounding factors. Foremost among these is the global escalation of stringent safety regulations. Governments and international automotive safety bodies are continuously mandating advanced lighting features to reduce rear-end collisions and improve night-time visibility. Features such as dynamic turn signals, adaptive rear lighting systems, and emergency stop signals are shifting from premium luxuries to standard requirements.
Simultaneously, the technology powering rear lights has transitioned significantly. Traditional halogen bulbs are rapidly being replaced by Light Emitting Diodes (LEDs) and Organic Light Emitting Diodes (OLEDs). LEDs offer superior energy efficiency, longer lifespans, faster response times, and exceptional design flexibility. This flexibility allows automakers to craft signature lighting designs such as continuous light strips across the tailgate which serve as a major selling point in modern passenger vehicles, especially electric vehicles (EVs).
Furthermore, the rise of electric and autonomous vehicles is fundamentally changing rear light architectures. Because EVs prioritize energy efficiency to maximize driving range, the low power consumption of LED and OLED systems makes them the industry standard.
Get a PDF Sample– https://www.theinsightpartners.com/sample/TIPRE00014496
Competitive Landscape and Key Players
The global automotive rear lights market is highly competitive, characterized by the presence of established tier-1 suppliers and innovative technology providers. These companies focus on continuous research and development to introduce lightweight, energy-efficient, and intelligent lighting solutions. Key players operating in the global market include:
HELLA GmbH and Co. KGaA
Koito Manufacturing Co., Ltd
Koninklijke Philips N.V.
Minda Industries Ltd.
OSRAM GmbH
Peterson Manufacturing Co.
Phoenix Lamps Ltd. (Suprajit Group)
Robert Bosch GmbH
STANLEY ELECTRIC CO., LTD.
Valeo
These industry leaders are actively engaging in strategic partnerships, mergers, acquisitions, and product launches to strengthen their market footprint and cater to the changing demands of global original equipment manufacturers (OEMs).
Future Outlook
The future of the automotive rear lights market points toward unprecedented levels of intelligence and digitalization. Looking ahead, rear lighting will transcend its traditional role of passive illumination to become an interactive communication interface. The integration of digital OLEDs and matrix LED technologies will enable rear lights to display customizable graphics, text symbols, and animations. This capability will be crucial for communicating intent or hazard warnings to pedestrians and autonomous vehicles sharing the road. Moreover, as the automotive ecosystem moves toward software-defined vehicles, rear lighting systems will be seamlessly tied into advanced driver assistance systems (ADAS) and vehicle-to-everything (V2X) communication networks. Consequently, the market is poised to experience sustained, high-value growth, transitioning from a commoditized safety component into a sophisticated, software-controlled tech hub.
Related Reports-
Automotive Rear End Module Market
Electric Light Commercial Vehicle Market
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients in getting solutions to their research requirements through our syndicated and consulting research services. We specialize in industries such as Semiconductor and Electronics, Aerospace and Defense, Automotive and Transportation, Biotechnology, Healthcare IT, Manufacturing and Construction, Medical Devices, Technology, Media, and Telecommunications, as well as chemicals and Materials.
Contact Us
If you have any queries about this report or if you would like further information, don’t hesitate to get in touch with us:
Contact Person: Ankit Mathur
E-mail: ankit.mathur@theinsightpartners.com
Phone: +1-646-491-9876