

Solvent borne adhesives remain a widely used bonding technology because of their ability to deliver strong adhesion across different materials. The Solvent Borne Adhesives Market was worth US$ 11.04 billion in 2025 and is forecast to reach US$ 16.71 billion by 2034, growing at a 5.32% CAGR during 2026-2034. Their performance characteristics continue to make them relevant for construction and manufacturing applications.
What Is Driving the Market?
The automotive sector is the first driver. Carmakers bond interior parts, exterior trims, and structural members. Solvent borne adhesives give strong bonds between metals, glass, plastics, and composites. The push for electric vehicles and lightweight materials raises the need for high-performance adhesives.
Get Sample PDF https://www.theinsightpartners.com/sample/TIPRE00006009
Packaging is the second. Strong demand in automotive and manufacturing, along with increased use in packaging, are the major drivers. Cartons, labels, films, and containers all need durable bonds. E-commerce and the rise in packaged goods keep demand high. These adhesives are used in food and beverage, consumer goods, and medical packaging.
Industrial use is the third. Construction, electronics, and automotive plants value adhesives that stay strong under heat, moisture, and chemical exposure. They bond many kinds of materials, which makes them versatile.
The report notes that a few valid concerns exist, but the overall benefits outweigh them.
Market Coverage
The report studies the market in three ways.
By Resin Type
By End-User Industry
Which Segment Leads?
The public report page does not name a single leading segment. It does show the range of resin types and industries at work.
Chloroprene rubber is known for fast, strong grab and is widely used in footwear, woodworking, and construction. Poly acrylate offers clarity and good aging. SBC resin adhesives are common in packaging and pressure-sensitive products.
By end-use, building and construction, packaging, transportation, and footwear all matter. Woodworking and electronics add more steady demand. The wide mix of uses helps the market stay stable when one sector slows. The full report gives the detailed segment split.
Which Region Leads?
The public report page does not state a regional leader. It covers North America, Europe, Asia Pacific, the Middle East and Africa, and South and Central America, along with key countries in each.
The United States is highlighted as a key market. The report links it to strength in the automotive sector, the packaging industry, and industrial uses.
Asia Pacific has a large manufacturing base in autos, footwear, and electronics. Europe brings strong regulation and advanced industrial demand. Emerging regions add growth as building and packaging activity picks up.
Which Companies Are Prominent?
The report profiles these leading players:
The list blends global adhesive leaders with specialty chemical firms and focused makers. Some offer wide product lines for many industries. Others concentrate on niche bonding needs.
The report says it studies competitive strategies and innovation developments among these firms. Competition centers on bond strength, durability, and the ability to serve fast-changing industries such as electric vehicles and electronics.
What Is Changing in the Market?
Specialty adhesives are the main trend. Rising demand for specialty adhesives in emerging applications is expected to be the key market trend. Electronics makers use them for circuit boards and displays. Medical device makers use them where parts must stay intact in harsh conditions. Textile makers use them as well.
Product innovation is a related shift. Industries want adhesives that bond unusual materials and resist chemicals or extreme temperatures. That need is driving new formulations.
Advanced formulations are the third change. Makers are adding nanotechnology and advanced resins to raise bond strength, heat resistance, and curing speed. Some firms are also building hybrid adhesives that combine solvent-based and water-based technologies. These aim for good processing with better environmental compatibility.
What Are the Investment Opportunities?
Electric vehicles are a top opportunity. EV makers want to cut weight and boost efficiency. Adhesives bond lightweight composites, metals, and plastics with strength and durability.
Construction is another. Adhesives are used in floors, roofs, windows, doors, and insulation. Growth in building and renovation, especially in emerging markets, raises demand for adhesives that last in tough conditions.
Aerospace and defense are the third. Aircraft, satellites, and military equipment face high altitude, rapid temperature swings, chemicals, and UV light. Adhesives that stay strong and flexible in those conditions are valued.
The total addressable market for 2026–2034 is estimated at about US$ 129.91 billion.
Companies that focus on specialty grades, EV bonding, and hybrid formulations have a lot to look forward to.
Related Reading / Reports
Explore additional research from The Insight Partners covering related adhesives and sealants markets:
Contact US
If you have any queries about this report or if you would like further information, please contact us:
Phone: +1-646-491-9876
E-mail: sales@theinsightpartners.com
The transition toward alternative fibre feedstocks is gaining traction as sustainability standards influence industrial sourcing decisions. The Non-Wood Fiber Market generated a value of US$ 397.89 million in 2025 and is expected to reach US$ 934.72 million by 2034, growing at a 9.95% CAGR during 2026-2034. Renewable resources including bamboo, straw, bagasse and cotton are helping broaden the industry's fibre options.
What Is Non-Wood Fiber?
Non-wood fibre is cellulose-rich material taken from agricultural residues and fast-growing plants instead of trees. Wheat and rice straw, sugarcane bagasse, bamboo and cotton all qualify. Manufacturers turn them into paper, textiles, construction boards and moulded consumer goods.
Request a Sample Copy of the Report: https://www.theinsightpartners.com/sample/TIPRE00027399
What Is Driving Demand for the Non-Wood Fiber Market?
So what is behind this acceleration? Pressure on forests comes first. Regulations such as the EU Deforestation Regulation push paper and packaging buyers to prove their pulp is traceable, and non-wood fiber sourcing offers a cleaner answer. Producers that once treated straw as a disposal problem now see a feedstock with a ready supply chain.
Cost and availability matter just as much. Sugar mills generate bagasse in huge volumes, and rice and wheat farmers in India and China have long struggled with what to do with stubble. Converting those residues into pulp cuts field burning and gives farmers a new income stream. What makes this particularly significant is that the fibre already exists, so no new plantation land is required.
Demand from end users adds further momentum. Brands are replacing single-use plastics with moulded fibre and paper-based formats, and bamboo-derived textiles appeal to shoppers who want softness alongside a lower footprint. Automotive interiors and construction panels are also adopting natural fibre composites to save weight and carbon, which broadens the non-wood fiber market well beyond paper.
Challenges remain. Seasonal harvests create uneven supply, straw carries silica that complicates pulping, and collection logistics can erode margins. Yet process innovation is steadily narrowing these gaps.
Segmentation Overview
By Source: Straw, Bagasse, Bamboo, Cotton and Others. Straw and bagasse benefit from abundant residue supply, while bamboo attracts investment thanks to rapid regrowth and strong fibre length. Cotton fibres serve premium paper and textile uses.
By Application: Paper Making, Textiles and Others. Paper making remains the anchor use for the non-wood fiber market, and textiles are gaining ground as bamboo and cotton-based yarns move into mainstream apparel.
By End-Use Industry: Textiles, Construction, Automotive, Consumer Goods and Others. Construction and automotive buyers value lightweight, low-carbon composites, and consumer goods makers use the fibre in packaging and tableware.
By Geography: North America, Europe, Asia Pacific, and South and Central America.
Key Market Players
These companies span the full value chain. Chempolis Oy is known for non-wood pulping technology, while EcoPlanet Bamboo Group and Bamboo Australia focus on bamboo cultivation. Zume Inc. and Bio-Lutions International AG turn agricultural residues into moulded packaging, and Shanghai Tenbro Bamboo Textile Co., Ltd. serves the textile side. Competition centres on securing dependable residue supply and improving fibre quality at scale.
Sustainability and Innovation Trends
Sustainability is the engine of the non-wood fiber market, and innovation is what makes it commercially viable. Chemical-light and biorefinery-style pulping methods are lowering water and energy use compared with conventional wood pulping. Blending non-wood pulp with recycled fibre helps mills stabilise quality, and moulded fibre technology keeps improving strength and moisture resistance for food-grade packaging.
Circular thinking is also taking hold. Mills near sugar refineries and farming belts are building local supply loops, which shortens transport distances and keeps emissions down. Expect more partnerships between agricultural cooperatives and pulp technology providers as the non-wood fiber market matures.
Buy Premium Report: https://www.theinsightpartners.com/buy/TIPRE00027399
Regional Outlook
Asia Pacific anchors the non-wood fiber market. China and India combine vast crop residue volumes, large paper industries and established bamboo and cotton textile bases, giving regional producers a natural cost edge. Europe follows with policy-led demand, as sustainability regulation and strong packaging standards favour alternative fibre sources. North America is building momentum through innovation in agricultural fibre pulping, specialty paper and moulded products. South and Central America holds promise thanks to sugarcane bagasse from its large sugar industry, and growing investment in bamboo plantations could widen its role over the forecast period.
Related Reports:
Specialty Paper Market Size, Share & Forecast 2031
Pulp and Paper Chemicals Market Size, Share, Scope 2034
Juco Bags Market Report by Share, Growth and Size: 2034
Polyester Fibers Market Size, Trends & Growth by 2034
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Phone: +1-646-491-9876
E-mail: sales@theinsightpartners.com
Also Available in: Korean | German | Japanese | French | Chinese | Italian | Spanish
The appeal of EPP foam lies in its ability to balance low weight with dependable durability and repeated use. The global Expandable Polypropylene (EPP) Foam Market was valued at US$ 1.43 billion in 2025 and is forecast to reach US$ 2.46 billion by 2034, advancing at a 6.21% CAGR from 2026 through 2034. Demand is increasing in sectors where impact absorption and sustainable material performance are key considerations.
What Is Expandable Polypropylene Foam?
EPP foam is made from tiny polypropylene beads that are expanded and then fused in a steam mould. The result is a light, closed-cell foam that absorbs repeated impacts and springs back to shape. It also resists water and chemicals and can be recycled. These traits keep the expandable polypropylene foam market strong in cars, logistics, and consumer goods.
Request a Sample Copy of the Report: https://www.theinsightpartners.com/sample/TIPRE00005981
What Is Driving Demand for EPP Foam?
Why is the expandable polypropylene foam market growing? Automotive lightweighting comes first. Carmakers must cut weight while keeping vehicles safe and comfortable. EPP goes into bumper cores, energy absorbers, seats, and interior parts. Electric vehicles raise its value, because lighter parts help offset battery weight. Global vehicle output reached about 96.4 million units in 2025, so the base of demand is large.
Reusable packaging is the second driver. Factories and logistics firms want protection that survives many trips. EPP resists repeated shocks, moisture, and handling, so it suits returnable containers, inserts, and dunnage. Cheap disposable cushioning cannot match that life span. Buyers now count cost over many cycles, which favours EPP.
Recycling rules add a third push. Carmakers, packaging users, and brands want recycled content without losing performance. Suppliers that offer traceable, consistent recycled grades should win more approvals. The steady move toward circular materials supports the expandable polypropylene foam market well beyond the near term.
Consumer products add variety. Sports gear, toys, and household items use EPP for low weight, comfort, and durability, which gives makers room for custom shapes.
Segmentation Overview
By Type: Low Density, High Density, and Porous PP. Low-density grades cut weight in interiors, inserts, and consumer goods. High-density grades give more stiffness and stability for structural parts and demanding packaging. Porous PP is the fast riser. It holds an estimated 16–20% share in 2025 and is expected to grow at 7.3–8.0% CAGR through 2034, thanks to uses that need airflow, sound absorption, and special cushioning.
By Application: Automotive, Packaging, Consumer Products, and Others. Automotive is the largest, with about 42–46% share in 2025. Packaging is the second big pool, driven by reusable transport systems.
By Geography: North America, Europe, Asia Pacific, and South and Central America.
Key Market Players
Competition mixes material makers, foam producers, and component suppliers. AkzoNobel, Kureha, Nouryon, and Sekisui Chemical bring specialist materials skills. Local plants, application engineering, and support for carmaker approvals now matter as much as price. Bead fusion quality and density control are key skills in the expandable polypropylene foam market.
Sustainability and Innovation Trends
Higher recycled content is the main trend. Future grades will use better-sorted post-industrial and post-consumer polypropylene, backed by strong quality checks. Closed-loop programmes for reusable dunnage and factory scrap may spread. Suppliers may offer several sustainability tiers instead of one recycled grade.
Local production is the second trend. In December 2025, JSP opened plants in Pune, India, and Ramos Arizpe, Mexico. That took its ARPRO foam network to 22 sites worldwide. Making foam near car plants cuts freight, speeds design changes, and supports just-in-time delivery. Expect similar moves in India, Mexico, Southeast Asia, and China.
Buy Premium Report: https://www.theinsightpartners.com/buy/TIPRE00005981
Regional Outlook
Asia Pacific leads, with an estimated 38–42% share in 2025 and about 7.1–7.8% CAGR through 2034. China produces the most vehicles, and India is a fast-rising base. North America holds roughly 27–31% share and grows at about 5.8–6.5% CAGR, supported by vehicle plants, EV parts, and reusable packaging. Europe holds around 23–27% share and grows at about 5.4–6.1% CAGR, with Germany leading and recycling rules shaping demand. South and Central America adds smaller but steady potential through vehicle assembly and logistics.
Related Reports:
Extruded Polypropylene (XPP) Foam Market Size & Trends 2034
Automotive Steel Market Size, Growth & Forecast 2034
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Phone: +1-646-491-9876
E-mail: sales@theinsightpartners.com
Also Available in: Korean | German | Japanese | French | Chinese | Italian | Spanish
Flat glass is at the intersection of several major industrial trends, including sustainable construction, automotive innovation, and renewable energy adoption. The Flat Glass Market is set to grow from US$ 160.11 billion in 2025 to US$ 323.18 billion by 2034, reflecting a projected 8.12% CAGR between 2026 and 2034.
What Is Flat Glass?
Flat glass is glass made in flat sheets, most often by the float process. Processors then cut it, temper it, laminate it, coat it, or seal it into insulated units. Basic sheets go into everyday glazing. Processed types add strength, safety, sound control, and heat performance. That shift from basic to processed glass is reshaping the flat glass market.
Request a Sample Copy of the Report: https://www.theinsightpartners.com/sample/TIPRE00017578
What Is Driving Demand for Flat Glass?
Why is the flat glass market growing so fast? Energy efficiency is a big reason. Building owners now judge glazing by lifetime energy use, not only by upfront cost. High-performance glass brings daylight, heat control, and comfort. Efficiency rules in Europe, North America, and Asia are raising the bar in both new builds and renovations.
Solar power is a second driver. Photovoltaic modules need durable, clear glass that keeps its performance for decades. Global solar capacity keeps rising, and that lifts demand for ultra-clear and tempered glass. Solar panels are the fastest-growing use in the report, with an estimated 10.0–11.2% CAGR through 2034.
Cars add a third push. Carmakers are fitting larger windshields, panoramic roofs, and acoustic glazing. Electric vehicles raise the value of glass per car, because buyers want quiet cabins and lighter parts. Safety rules also favour laminated and tempered products across construction and transport.
Replacement demand supports growth too. Older glazing systems in aging buildings are being swapped for better units. Together, these forces help the flat glass market grow faster than many other building materials.
Segmentation Overview
By Product: Basic, Tempered, Laminated, Insulated, and Others. Basic glass is the base material for downstream processing. Tempered glass offers higher strength and thermal shock resistance for facades, doors, and vehicles. Laminated glass holds together after breakage and adds security and sound control. Insulated glass cuts heat transfer and helps buildings save energy.
By Application: Architectural, Automotive, and Others. Architectural use is the largest base, spanning windows, facades, doors, and interiors. Automotive demand centres on windshields, side windows, and roofs. Other uses include solar modules, appliances, and electronics.
By Geography: North America, Europe, Asia Pacific, and South and Central America.
Key Market Players
Scale, reach, and processing skill decide who wins in the flat glass market. AGC blends architectural, automotive, and specialty strengths. Saint-Gobain brings a wide building materials range. Türkiye Şişe ve Cam is a leading international producer, while Guardian and Nippon Sheet Glass add regional and specialist depth. Cardinal is strong in North American architectural glazing. SCHOTT focuses on specialty glass. Almana, Dallas Flat Glass, and CEVITAL serve regional needs.
Sustainability and Innovation Trends
Glass making burns a lot of energy, so cleaner furnaces matter. Producers are using more recycled glass, called cullet, which cuts melting energy. Closed-loop systems collect waste glass from buildings, cars, and solar panels and feed it back into production. Access to clean cullet could become a competitive edge.
Furnace technology is changing too. Hybrid furnaces mix electricity with conventional fuel to lower direct carbon emissions. The AGC and Saint-Gobain VOLTA project has shown hybrid melting at industrial scale. Over time, lower-carbon glass may become a buying rule for architects, carmakers, and solar makers.
Buy Premium Report: https://www.theinsightpartners.com/buy/TIPRE00017578
Regional Outlook
Asia Pacific is the volume leader, with an estimated 50–55% share in 2025 and about 8.7–9.6% CAGR through 2034. China dominates, and India is gaining fast. North America holds roughly 18–22% share and grows at about 7.4–8.2% CAGR, backed by renovation, vehicles, and solar. Europe holds around 17–21% share and grows at about 6.5–7.4% CAGR, with low-carbon goals shaping demand. South and Central America adds steady room through construction and vehicle output.
Related Reports:
Architectural Glass Market Trends, Demand & Growth by 2034
Advanced Glass Market Size, Share & Forecast 2034
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Phone: +1-646-491-9876
E-mail: sales@theinsightpartners.com
Also Available in: Korean | German | Japanese | French | Chinese | Italian | Spanish
Flat steel may begin as a basic sheet or coil, but its applications span some of the world's most important industries, including automotive, construction, appliances, and energy. The Flat Steel Market is forecast to expand from US$ 709.05 billion in 2025 to US$ 1,125.39 billion by 2034, recording a 5.27% CAGR during 2026–2034. Continued infrastructure spending, rising vehicle production, and growing adoption of higher-value grades are expected to remain central to market growth.
What Is Flat Steel?
Flat steel covers sheets, coils, strips, and plates made by rolling steel into flat forms. Mills make it through two main routes. The Basic Oxygen Furnace suits large integrated plants. The Electric Arc Furnace melts scrap and offers flexible, lower-emission production. Buyers pick the product by strength, surface finish, coating, and formability, which keeps the flat steel market diverse.
Request a Sample Copy of the Report: https://www.theinsightpartners.com/sample/TIPRE00009458
What Is Driving Demand for Flat Steel?
What keeps the flat steel market moving up? Infrastructure comes first. Governments are renewing bridges, ports, rail lines, and cities. Hot rolled sheets and coils go into structures, roofing, and cladding. Many firms also want factories closer to customers, which adds steel demand in new regions.
Cars are the second driver. Carmakers want lighter bodies that stay safe and resist rust. That favours advanced high-strength and coated flat steel. Electric vehicles raise the bar on forming and precision. Mills with strong rolling, annealing, and coating skills win more of this business.
Electrification is the third driver. Grids, motors, transformers, and renewable plants need electrical sheet and strip with tightly controlled magnetic properties. These grades are harder to make and harder to replace, so they earn better margins than standard products.
Appliances and machinery add steady volume. Fridges, washers, ovens, tractors, and industrial equipment need formable, coated steel with a consistent surface. Producers that mix product lines well can protect margins even when prices swing in the flat steel market.
Segmentation Overview
By Process: Basic Oxygen Furnace and Electric Arc Furnace. The Basic Oxygen Furnace stays central for large-scale production. The Electric Arc Furnace is gaining ground where scrap, power costs, and emission goals make it attractive.
By Product: Hot Rolled Flat Sheets, Hot Rolled Coils, Electrical Sheet and Strip, Metallic Coated Sheet and Strip, Non-Metallic Coated Sheet and Strip, Tin Plates, and Others. Hot rolled coils are a core format for shipping and further rolling. Electrical sheet and strip is the fast riser, holding about 6–9% share in 2025 and growing at 6.4–7.2% CAGR through 2034. Coated products resist corrosion in cars and buildings. Tin plates serve food and drink packaging.
By End-Use: Building and Infrastructure, Automotive and Transportation, Mechanical Equipment, Electrical Appliances, Agriculture Equipment, and Others. Building and infrastructure is the largest group, with about 38–42% share in 2025.
By Geography: North America, Europe, Asia Pacific, and South and Central America.
Key Market Players
Competition in the flat steel market now turns on product mix, regional capacity, and readiness for decarbonization. China Baowu and Ansteel lead through sheer scale in China. ArcelorMittal, Nippon Steel, Tata Steel, JFE, POSCO, and U.S. Steel widen their value-added ranges. Gerdau and thyssenkrupp add strength in regional and specialty markets. Investment is flowing into electric arc capacity, galvanizing, electrical steel, and finishing lines.
Sustainability and Innovation Trends
Buyers increasingly ask how steel was made. Embedded emissions, recycled content, and traceability now shape purchase choices. Electric arc production, hydrogen-based reduction, and renewable power will influence who wins. Conventional plants will stay important for years, so change should arrive step by step. Mills that can prove lower emissions may earn premium pricing from customers with climate targets.
Digital tools are the second trend. Sensors, AI, and digital twins can spot surface defects early and predict equipment problems. This moves quality control from checking after the fact to acting before problems appear, which matters for auto and appliance buyers.
Buy Premium Report: https://www.theinsightpartners.com/buy/TIPRE00009458
Regional Outlook
Asia Pacific dominates, with an estimated 68–72% share in 2025 and about 5.8–6.6% CAGR through 2034. China leads, while India is the fastest-growing major economy. North America holds roughly 10–13% share and grows at about 3.8–4.5% CAGR, helped by infrastructure renewal and vehicle localization. Europe holds around 13–16% share and grows at about 3.5–4.2% CAGR, with decarbonization shaping choices. South and Central America adds steady demand from construction and manufacturing.
Related Reports:
Galvanized Steel Market Share, Demand & Growth by 2034
Automotive Steel Market Size, Growth & Forecast 2034
Steel Market Trends, Size & Forecast by 2034
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Contact Us:
If you have any queries about this report or if you would like further information, please contact us:
Phone: +1-646-491-9876
E-mail: sales@theinsightpartners.com
Also Available in: Korean | German | Japanese | French | Chinese | Italian | Spanish
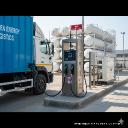
As energy markets diversify, the Compressed Natural Gas Market is emerging as a key player in the transition toward alternative fuels. Blending economic benefits with environmental advantages, CNG is increasingly preferred by consumers and industries aiming for sustainable and efficient energy solutions.
Transportation Sector: The Primary Growth Engine
The transportation sector is the dominant demand driver for CNG, as governments and fleet operators worldwide seek alternatives to diesel and petrol in pursuit of lower operating costs and reduced carbon emissions. Natural gas vehicles (NGVs) have gained significant traction in public bus fleets, municipal waste collection, long-haul trucking, and taxi networks across Asia, South America, and Europe. Sales of natural gas vehicles are projected to cross 35 million units, reinforcing the central role of transportation in driving CNG market expansion.
Technological advancements in CNG engine efficiency and high-pressure composite storage cylinders are making CNG vehicles increasingly competitive with their conventional counterparts. Lighter, safer, and more cost-effective storage systems are reducing the total cost of ownership for NGV operators, broadening the appeal of CNG adoption.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00008136
Power Generation and Distributed Energy
The power generation sector represents a growing application for CNG, particularly as electricity demand rises globally and primary gas-producing regions in the Middle East, United States, and Russia invest in gas-based power infrastructure. The trend toward distributed power generation — where localized CNG-fueled generators serve industrial, commercial, and remote community needs — is emerging as a significant market driver, reducing dependence on centralized grid infrastructure and improving energy resilience.
Order a Copy of this Research Study @ https://www.theinsightpartners.com/buy/TIPRE00008136
Infrastructure Expansion and Green CNG
Expansion of CNG refueling infrastructure is one of the most pressing prerequisites for accelerated market growth. Governments in India, China, Iran, and across Latin America have invested substantially in CNG station networks to support growing NGV fleets. Mobile refueling units and on-site fleet refueling stations are also broadening access to CNG for operators in areas not yet served by fixed infrastructure.
Green CNG — produced from biogas sourced from agricultural waste, landfill gas, and organic residues — is gaining commercial momentum as a zero-carbon or carbon-negative alternative. These renewable variant leverages existing CNG distribution infrastructure, accelerating its market penetration and aligning CNG more firmly with net-zero energy transition goals.
Regional Insights and Competitive Landscape
Asia Pacific leads global CNG consumption, with China, India, Iran, and Pakistan operating the world's largest NGV fleets. Europe and North America are witnessing steady growth driven by decarbonization policy and heavy-duty transport electrification challenges. With a projected CAGR of 10.5% through 2031, the CNG market presents compelling opportunities for infrastructure developers, vehicle manufacturers, gas utilities, and clean energy investors seeking exposure to a high-growth, lower-emission fuel segment.
Browse Trending Reports:
Oil And Gas Exploration And Production Market
Exploration And Drilling Security Market
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Also Available in : Korean German Japanese French Chinese Italian Spanish
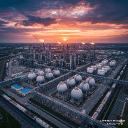
As global energy systems evolve, the Natural Gas Liquids Market is positioned for steady growth supported by favorable supply trends and expanding export capacities. Enhanced infrastructure development, including fractionation plants and export terminals, is enabling producers to capitalize on emerging opportunities in regional and international markets.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00007834
Key Growth Drivers
The petrochemical industry's insatiable demand for NGL-derived feedstocks is the single largest driver of market growth. Ethane, the most abundant NGL, is the primary feedstock for ethylene production — the building block for polyethylene plastics widely used in packaging, consumer goods, and industrial applications. As global plastic demand continues to rise, particularly in Asia, the petrochemical sector's appetite for ethane and other NGLs is expected to intensify through 2031.
The dramatic expansion of shale gas production in the United States has also been transformative. Associated NGLs extracted alongside shale gas have significantly increased the supply of ethane, propane, and butane, driving down feedstock costs and encouraging investment in new cracker plants and petrochemical complexes along the US Gulf Coast. This trend is reinforcing America's position as the world's leading NGL producer and exporter.
Alternative Fuel and Energy Transition Opportunities
Propane and butane are increasingly being adopted as cleaner alternatives to traditional fossil fuels in transportation, agriculture, and residential heating. Propane-powered vehicles are promoted in several markets as lower-emission substitutes for gasoline and diesel, while LPG (liquefied petroleum gas, primarily propane and butane) continues to play a vital role in cooking and heating for off-grid households in developing countries.
The rising interest in renewable CNG and bioLPG — produced from organic waste and agricultural residues — presents additional growth avenues for the NGL market as it aligns with global decarbonization objectives. These bio-based alternatives benefit from existing NGL distribution infrastructure, accelerating their commercial viability.
Order a Copy of this Research Study @ https://www.theinsightpartners.com/buy/TIPRE00007834
Regional Insights
North America dominates NGL production, underpinned by prolific shale basins including the Permian, Marcellus, and Haynesville. The Middle East — led by Saudi Arabia and Qatar — is also a major NGL producer, leveraging large gas processing operations associated with oil and gas production. Asia Pacific is the fastest-growing consumption region, driven by surging demand from its petrochemical, transportation, and residential sectors.
Competitive Landscape and Outlook
The NGL market is expected to see continued investment in processing infrastructure, export terminals, and new petrochemical capacity as producers seek to monetize growing NGL supplies. With energy security concerns and the petrochemical boom both driving demand, the market's 5.2% CAGR through 2031 signals a compelling growth story for investors, producers, and industry stakeholders positioned along the NGL value chain.
Browse Trending Reports:
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Also Available in : Korean German Japanese French Chinese Italian Spanish
With energy markets experiencing seasonal shifts and geopolitical uncertainties, the Oil Storage Market remains critical for balancing supply-demand imbalances and mitigating price fluctuations. Investments in advanced tank infrastructure and logistics support systems are positioning industry players to address future challenges and capitalize on emerging opportunities.
Market Overview and Segmentation
The oil storage market encompasses a broad range of infrastructure used to store crude oil and refined petroleum products at various points along the supply chain. The report segments the market by type — including crude oil, middle distillates, aviation fuel, and other refined products — by material (steel, fiber-reinforced plastic, and carbon steel), and by product design, covering open top, fixed roof, floating roof, and other tank configurations.
Key players shaping this market include Oiltanking GmbH, CST Industries, Containment Solutions, ZCL Composites (Shawcor), Belco Manufacturing, and Synalloy Corporation, alongside global oil majors and independent terminal operators such as Royal Vopak and China National Petroleum Corporation.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00006233
Primary Growth Drivers
The most fundamental driver of oil storage demand is the continued growth of global oil consumption. Despite the accelerating transition to renewable energy, oil remains a primary fuel for transportation, industrial processes, and heating across much of the world — particularly in developing economies where energy demand growth is fastest. As consumption rises, so does the need for secure, efficient storage infrastructure at refineries, distribution hubs, and strategic reserves.
Geopolitical instability and price volatility in global oil markets have further elevated the strategic importance of storage capacity. Companies and governments alike are expanding storage reserves to hedge against supply disruptions, manage price arbitrage opportunities, and ensure energy security. The COVID-19 pandemic — which caused an unprecedented surge in storage demand as oil production briefly exceeded consumption — underscored the critical role of storage infrastructure in managing supply chain shocks.
Technological Advancements
The oil storage sector is being transformed by smart technology adoption. IoT-enabled sensors, automated monitoring systems, and digital management platforms now allow real-time tracking of storage conditions including temperature, pressure, and product quality. These innovations improve safety, reduce operational costs, and help prevent spills or product degradation. Floating roof tank designs are gaining preference for volatile products, as they reduce evaporation losses and associated emissions.
Emerging Market Opportunities
Rapid industrialization and urbanization in Asia Pacific, the Middle East, and Africa are creating substantial demand for new oil storage infrastructure. Countries expanding their refining capacities and seeking energy security through strategic petroleum reserves represent significant investment opportunities. Additionally, the gradual integration of renewable energy and biofuels into the energy mix is prompting operators to adapt storage infrastructure to accommodate a broader range of fuel types.
Order a Copy of this Research Study @ https://www.theinsightpartners.com/buy/TIPRE00006233
Competitive Landscape and Regional Outlook
Asia Pacific is expected to be the fastest-growing region for oil storage infrastructure through 2031, driven by China, India, and Southeast Asian nations expanding their energy storage capacity. North America and Europe maintain large, mature storage networks while investing in upgrades and compliance-driven modernization. The report identifies increasing expansion of refineries and petrochemical plants as the defining future trend for the oil storage market, cementing its role as a foundational pillar of global energy security infrastructure.
Browse Trending Reports:
Deepwater Hydrocarbon Exploration Market
Liquified Petroleum Gas Market
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Also Available in : Korean German Japanese French Chinese Italian Spanish
Rising environmental awareness and asset retirement cycles are reshaping the Offshore Decommissioning Market across global offshore basins. Industry participants are adopting integrated project management and digital planning tools to improve efficiency and reduce risk. As more platforms reach decommissioning age, demand for specialized expertise continues to grow.
Regulatory and Environmental Drivers
Government regulations across major offshore oil-producing regions — notably the North Sea, Gulf of Mexico, and Asia Pacific — are mandating timely and responsible decommissioning of end-of-life assets. In the UK, for example, the Oil and Gas Authority (OGA) has enforced strict timelines and cost-sharing frameworks, while Norway's stringent environmental standards continue to set global benchmarks for sustainable decommissioning practice.
The drive toward eco-friendly decommissioning is gaining momentum as regulators and communities demand that operators minimize seabed disturbance, manage hazardous waste responsibly, and explore opportunities for reef creation and marine habitat preservation through derogation processes.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00006140
Innovation and Technology Transformation
AI-powered robotics and autonomous underwater vehicles (AUVs) are revolutionizing decommissioning efficiency. These technologies enable precise assessment, cutting, and removal operations in hazardous environments with reduced risk to human workers and lower overall project costs. Digital twins and advanced simulation tools are being used for project planning and risk management, shortening decommissioning timelines and improving budgetary outcomes.
The adoption of collaborative industry approaches — whereby multiple operators pool resources and share infrastructure removal costs — is also gaining traction. Such frameworks are particularly relevant in mature basins like the North Sea, where hundreds of structures are scheduled for removal over the coming decade.
Circular Economy Opportunities
A significant emerging opportunity lies in the application of circular economy principles to decommissioning. Steel and other materials recovered from decommissioned platforms can be recycled and repurposed, generating revenue that helps offset project costs. Repurposing offshore structures for wind energy foundations, artificial reefs, or hydrogen production platforms represents a creative convergence of the energy transition and decommissioning requirements.
Order a Copy of this Research Study @ https://www.theinsightpartners.com/buy/TIPRE00006140
Regional Insights and Outlook
Europe — particularly the UK and Norway — represents the most mature decommissioning market due to the age profile of North Sea infrastructure. However, Asia Pacific and the Middle East are emerging as high-activity regions as offshore assets installed in the 1970s and 1980s reach decommissioning age. The global pipeline of decommissioning projects is expected to remain substantial through 2031 and beyond, providing long-term growth visibility for service providers that can deliver safe, cost-effective, and sustainable solutions.
Browse Trending Reports:
Floating Liquefied Natural Gas Market
Oil Storage Tank Service Market
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Also Available in : Korean German Japanese French Chinese Italian Spanish
The Global Bunker Fuel Market is set to experience significant transformation over the 2025–2031 forecast period, driven by the convergence of regulatory evolution, digital innovation, and a post-pandemic resurgence in global maritime trade. According to a comprehensive research report published by The Insight Partners, the market is poised for steady growth as shipping companies navigate the complex interplay between cost management, environmental compliance, and operational efficiency.
Request Sample Pages of this Research Study @ https://www.theinsightpartners.com/sample/TIPRE00003672
Key Growth Drivers
One of the most compelling forces propelling the bunker fuel market is the recovery of global trade. As international shipping volumes continue to rebound following the disruptions caused by the COVID-19 pandemic, the demand for bunker fuel solutions has grown correspondingly. Container shipping lanes, bulk commodity routes, and tanker operations all require consistent and competitive fuel supply, making demand robust across segments.
Digital transformation is also reshaping the fuel management landscape. Advanced platforms for bunker fuel price transparency and comparison are empowering shipping companies to make informed purchasing decisions, reducing costs and improving supply chain efficiency. Artificial intelligence, IoT-driven monitoring systems, and smart procurement tools are being adopted across major bunkering hubs to optimize fuel management.
Sustainability and Regulatory Tailwinds
The market is witnessing a pivotal shift toward eco-friendly bunker fuels in response to tightening international regulations. The International Maritime Organization's (IMO) sulfur cap — which requires vessels to use fuel with a maximum sulfur content of 0.5% globally — has dramatically accelerated the uptake of low-sulfur and alternative fuels such as LNG, biofuels, and methanol. This regulatory shift has created new demand dynamics, particularly for MGO/MDO, which is compliant with global emissions standards.
Shipping companies are increasingly investing in dual-fuel engine technologies and scrubber installations to meet environmental mandates while managing fuel costs. The green transition presents a major opportunity for market participants who can provide sustainable bunker fuel solutions tailored to eco-conscious shipping operators.
Order a Copy of this Research Study @ https://www.theinsightpartners.com/buy/TIPRE00003672
Regional Insights
Asia Pacific dominates the bunker fuel market, anchored by major bunkering hubs in Singapore, China, and South Korea. North America and Europe also hold significant market positions, driven by well-established maritime trade routes and stricter Emission Control Area (ECA) compliance requirements. The Middle East and South and Central America are identified as high-potential emerging regions, where expanding port infrastructure and rising trade activity are expected to boost bunkering demand through 2031.
Competitive Landscape and Outlook
The bunker fuel market is moderately consolidated, with Gazpromneft Marine Bunker, LUKOIL, Marathon Petroleum, Neste Oyj, and Valero Energy Corporation competing alongside global energy majors. Companies are differentiating themselves through digital service platforms, sustainable product portfolios, and strategic positioning at key bunkering ports worldwide.
As the maritime industry charts its course toward decarbonization, the bunker fuel market stands at an inflection point. The report's forecast period through 2031 captures a market in transition — one where traditional heavy fuel oil faces mounting headwinds, while cleaner alternatives are rapidly gaining traction. Stakeholders across the value chain, from producers and distributors to technology providers and investors, will need to adapt swiftly to capitalize on the opportunities this dynamic market presents.
Browse Trending Reports:
Natural Gas Fueling Station Market
Microbial Enhanced Oil Recovery Market
About The Insight Partners
The Insight Partners is among the leading market research and consulting firms in the world. We take pride in delivering exclusive reports along with sophisticated strategic and tactical insights into the industry. Reports are generated through a combination of primary and secondary research, solely aimed at giving our clientele a knowledge-based insight into the market and domain. This is done to assist clients in making wiser business decisions. A holistic perspective in every study undertaken forms an integral part of our research methodology and makes the report unique and reliable.
Also Available in : Korean German Japanese French Chinese Italian Spanish